Case study · Loan self-assessment · Product Build
Borrower CopilotLoan self-assessment Case Study
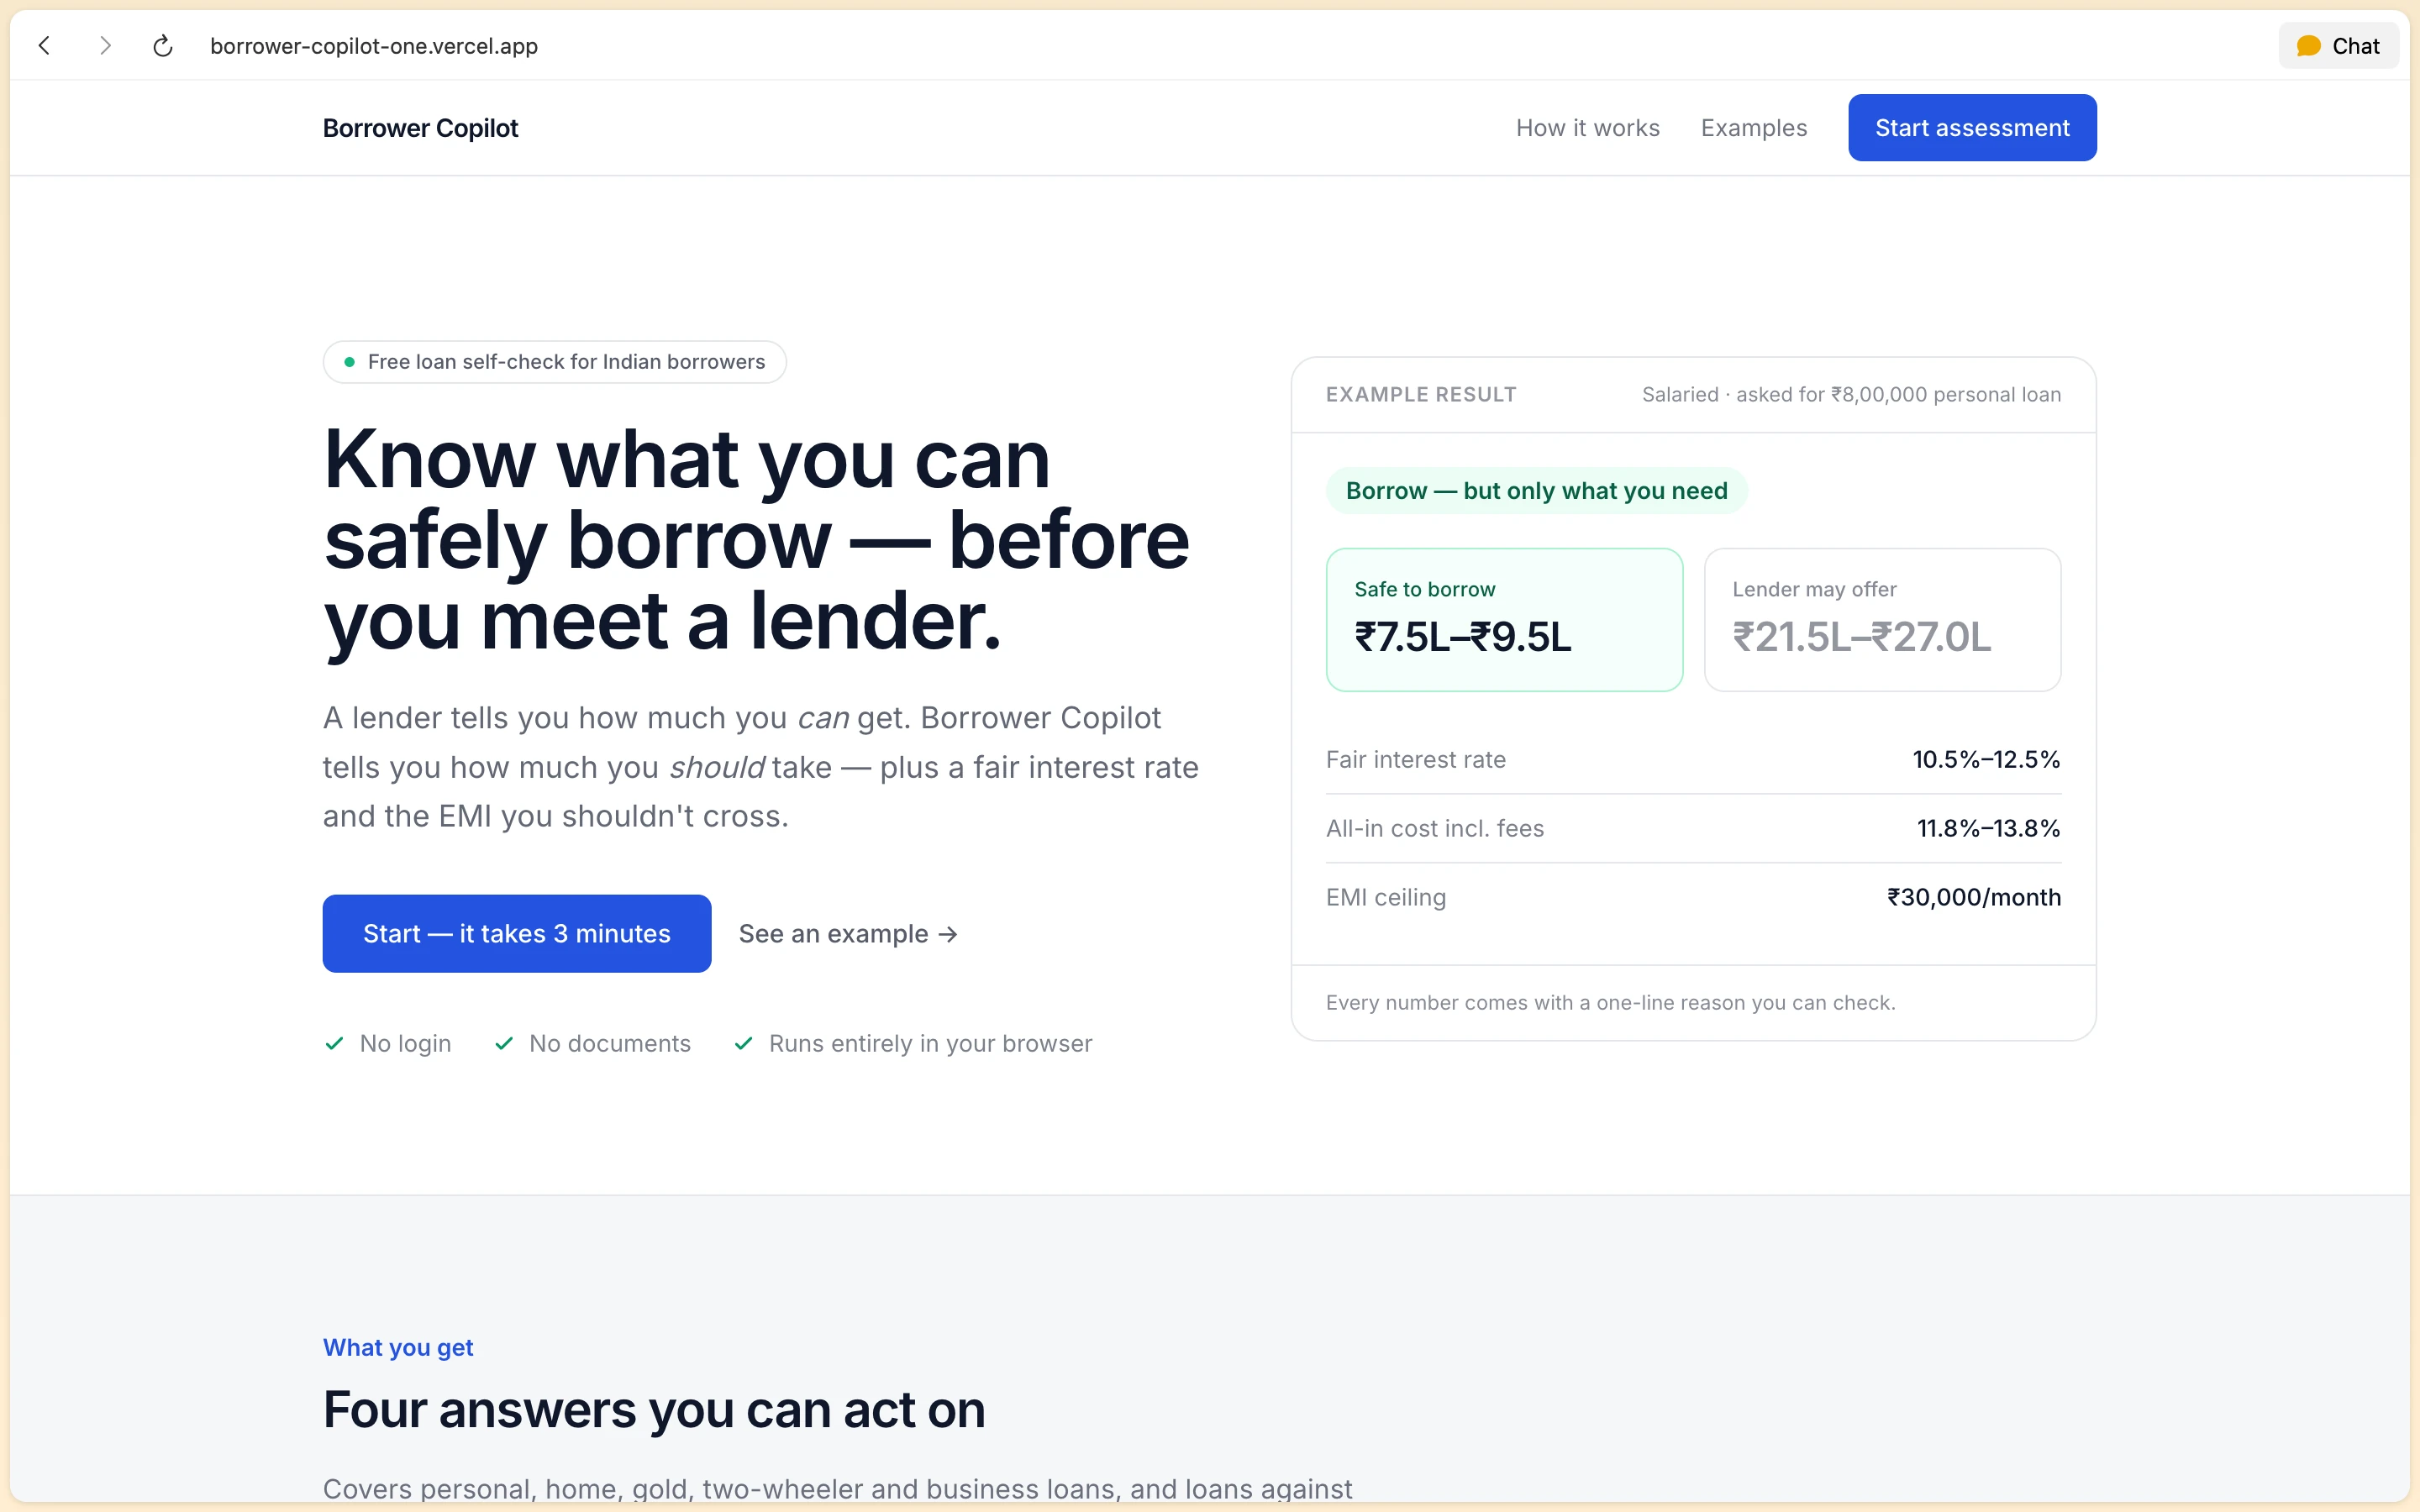
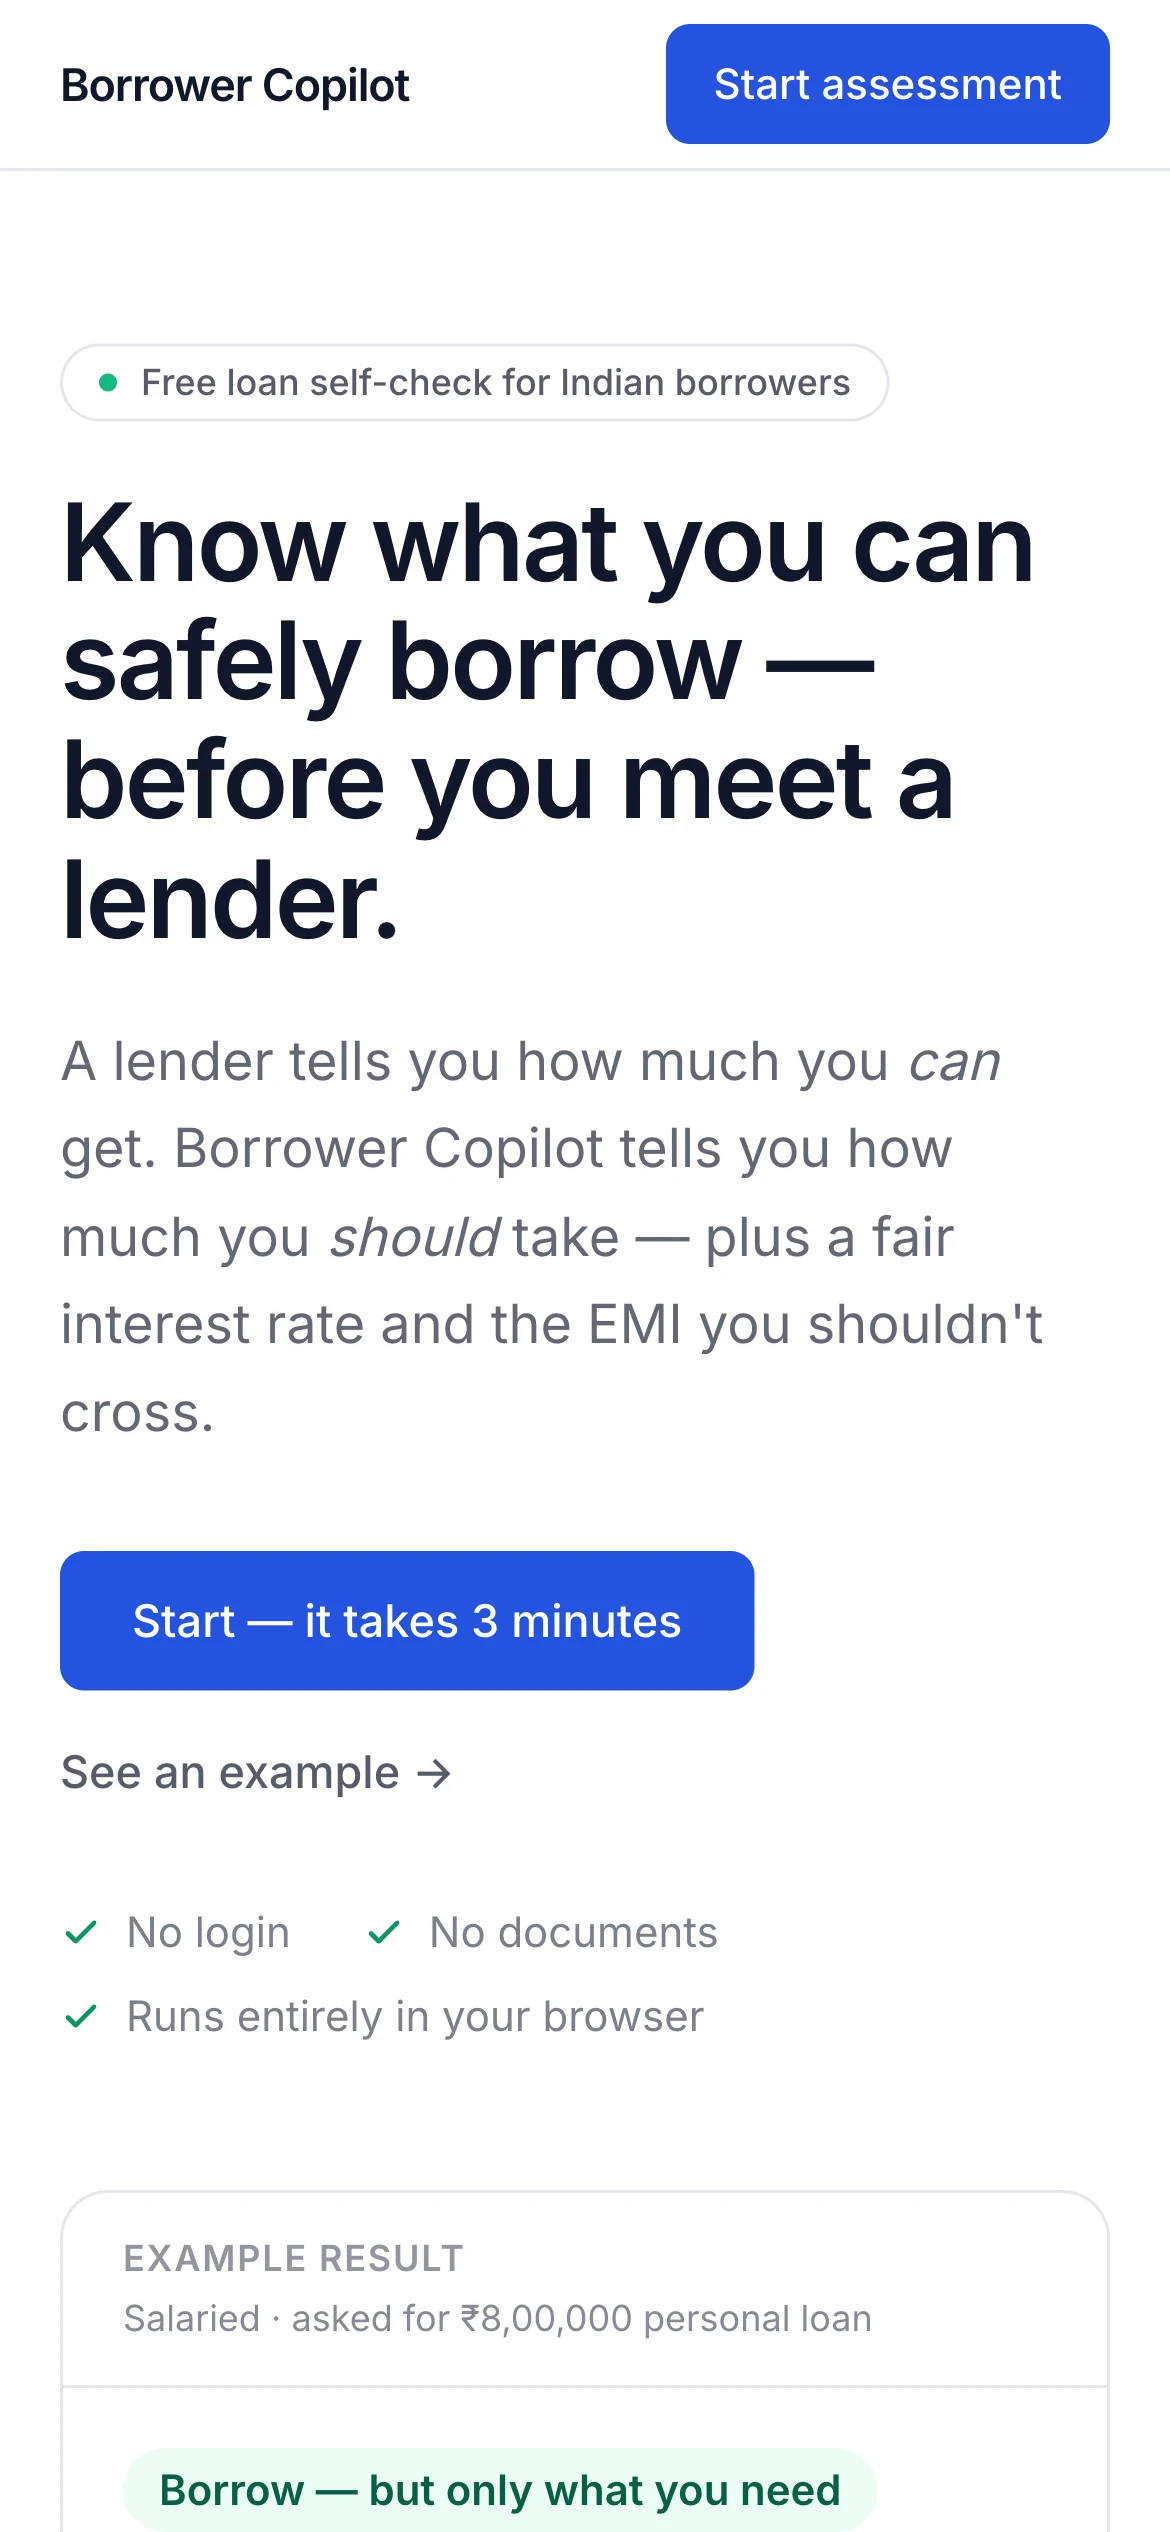
A loan self-check for Indian borrowers: about nine adaptive questions, then a verdict, a safe amount next to the lender's number, a fair rate and an EMI ceiling, all computed in the browser.
- Type
- Built to a written brief
- Role
- Rules engine, design, frontend, deployment
- Status
- Live on Vercel
- Service
- Product Build
- Last updated
The problem
A lender tells a borrower how much they can get, not how much they can safely repay, and the borrower usually walks into the branch with only the lender's number.
What I built
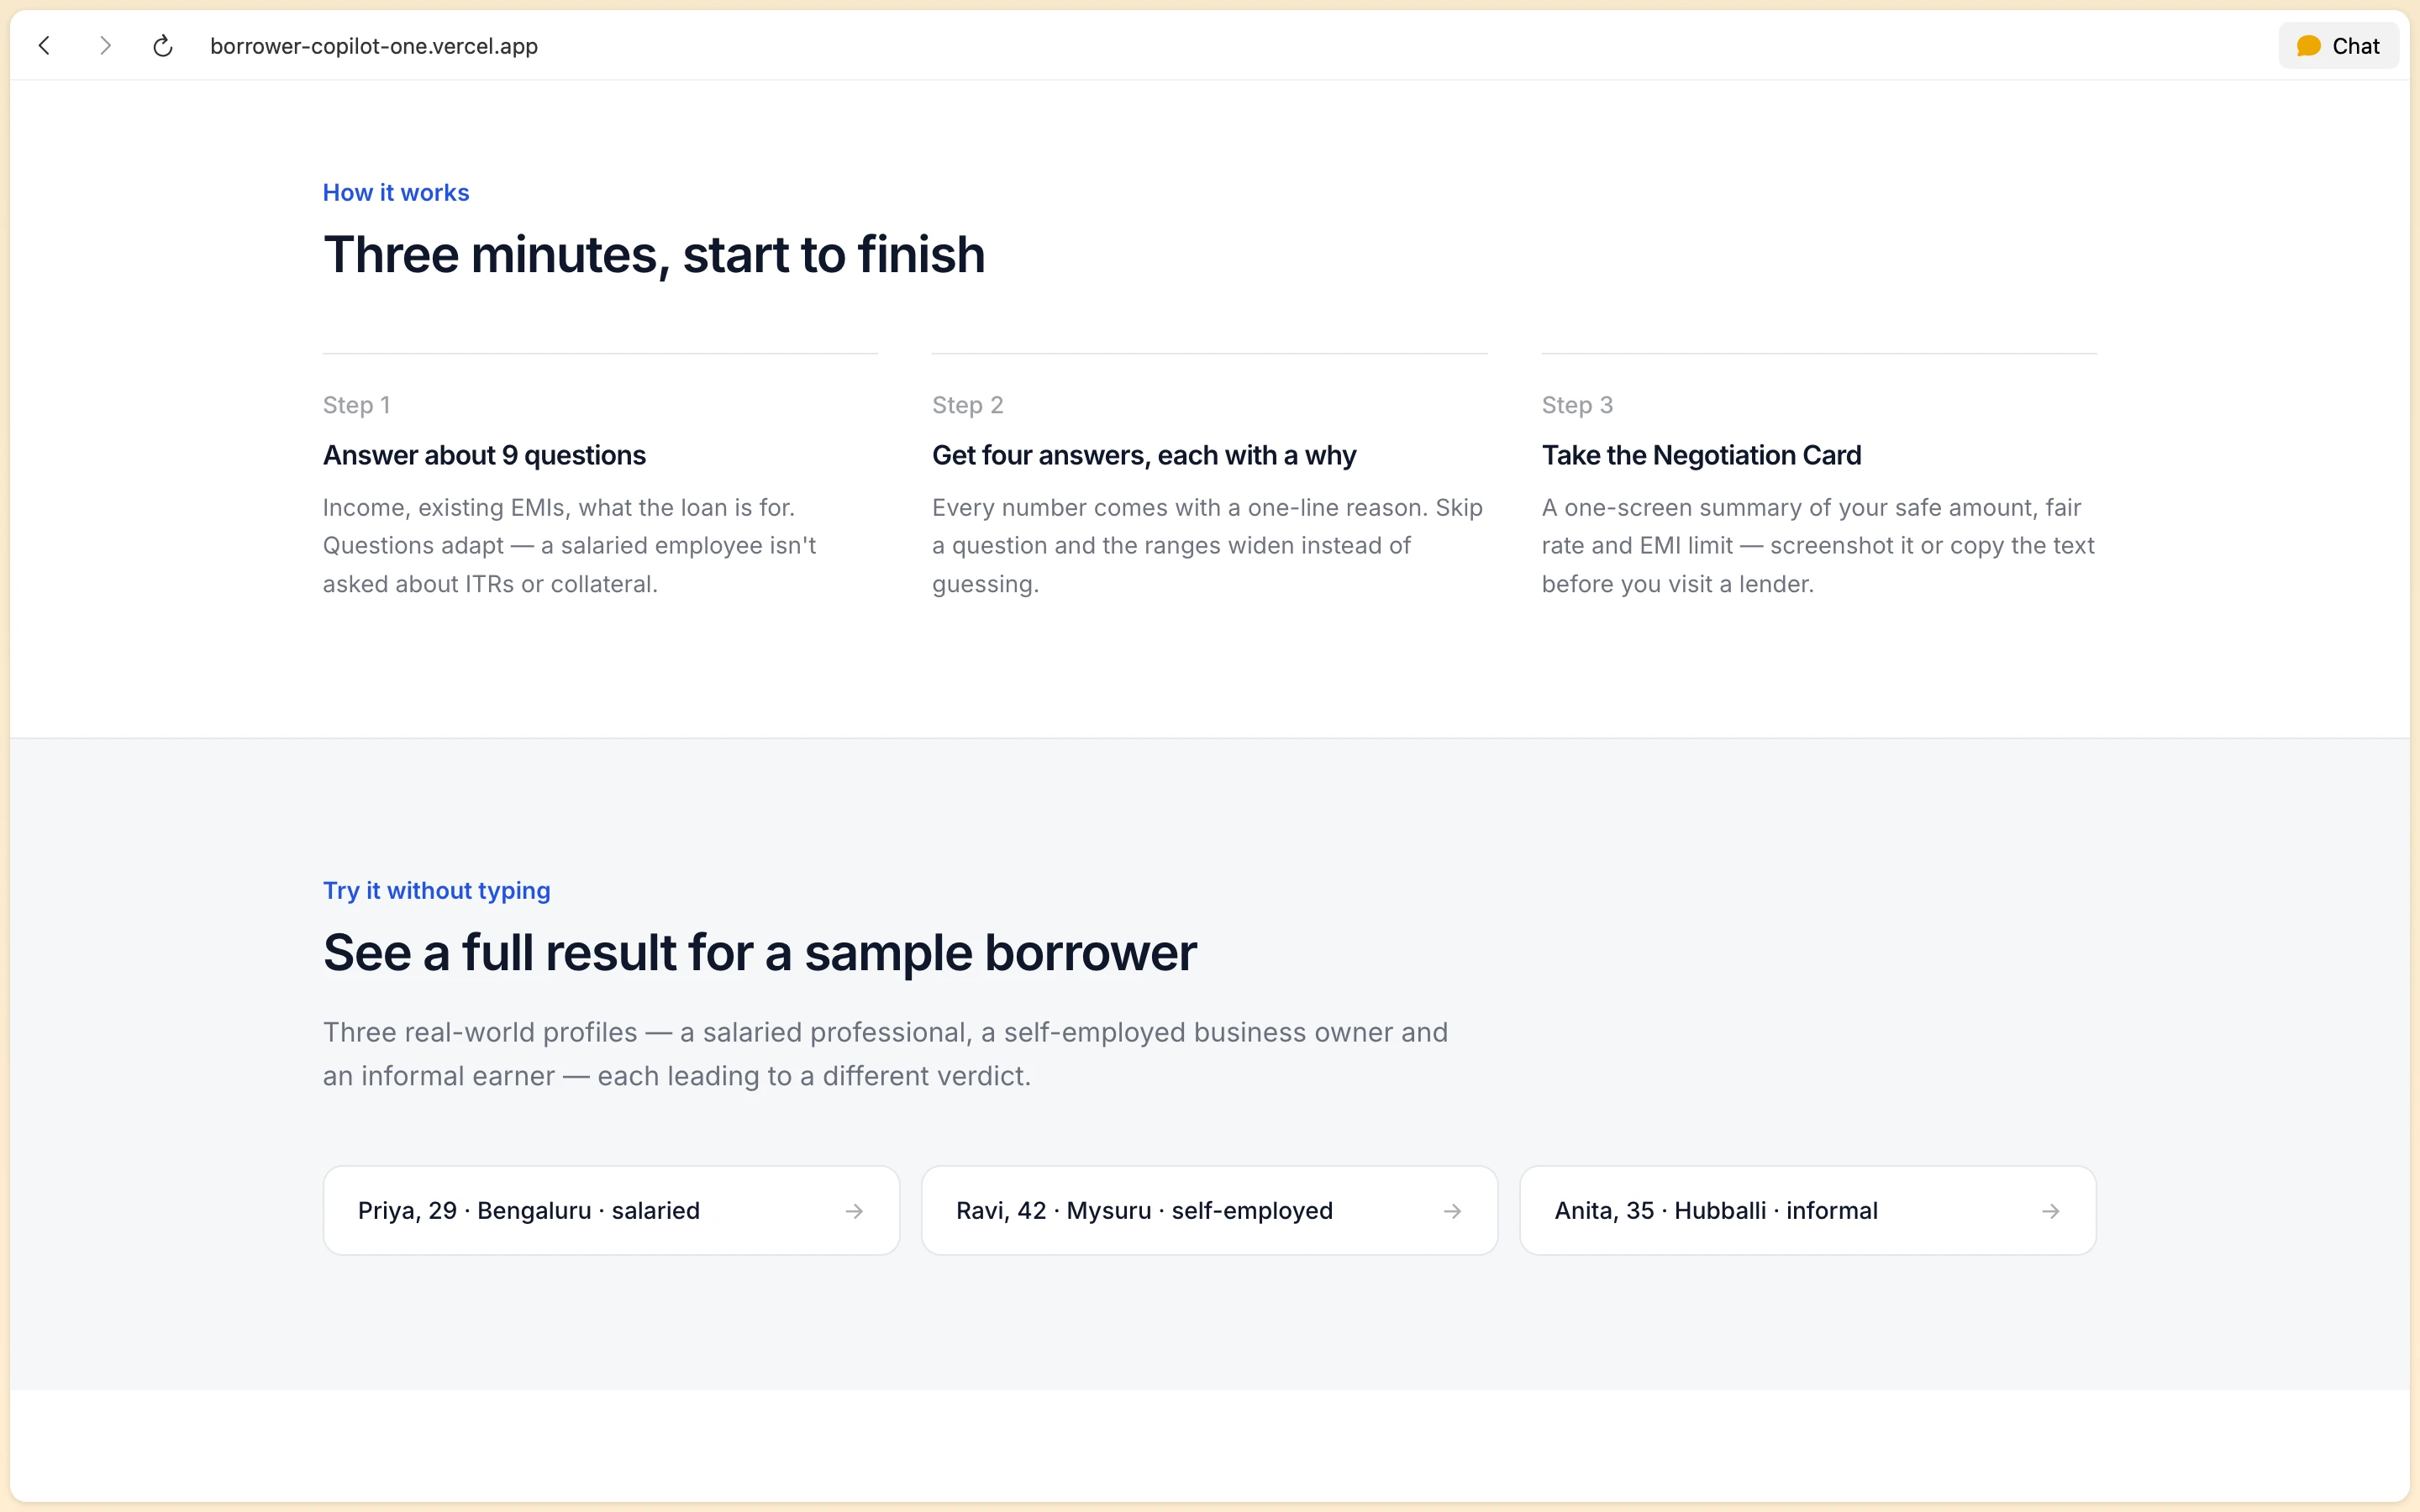
Borrower Copilot asks about nine questions that adapt to the borrower (a salaried employee isn't asked about ITRs or collateral) and runs the answers through a deterministic rules engine. It returns four outputs, each with a one-sentence reason, plus a Negotiation Card to show a lender. There is no login and no backend: every number is calculated in the browser.
Walkthrough
See it working
From the first question to the Negotiation Card, in one minute.
What it does
The features that matter
What it actually does, one feature at a time.
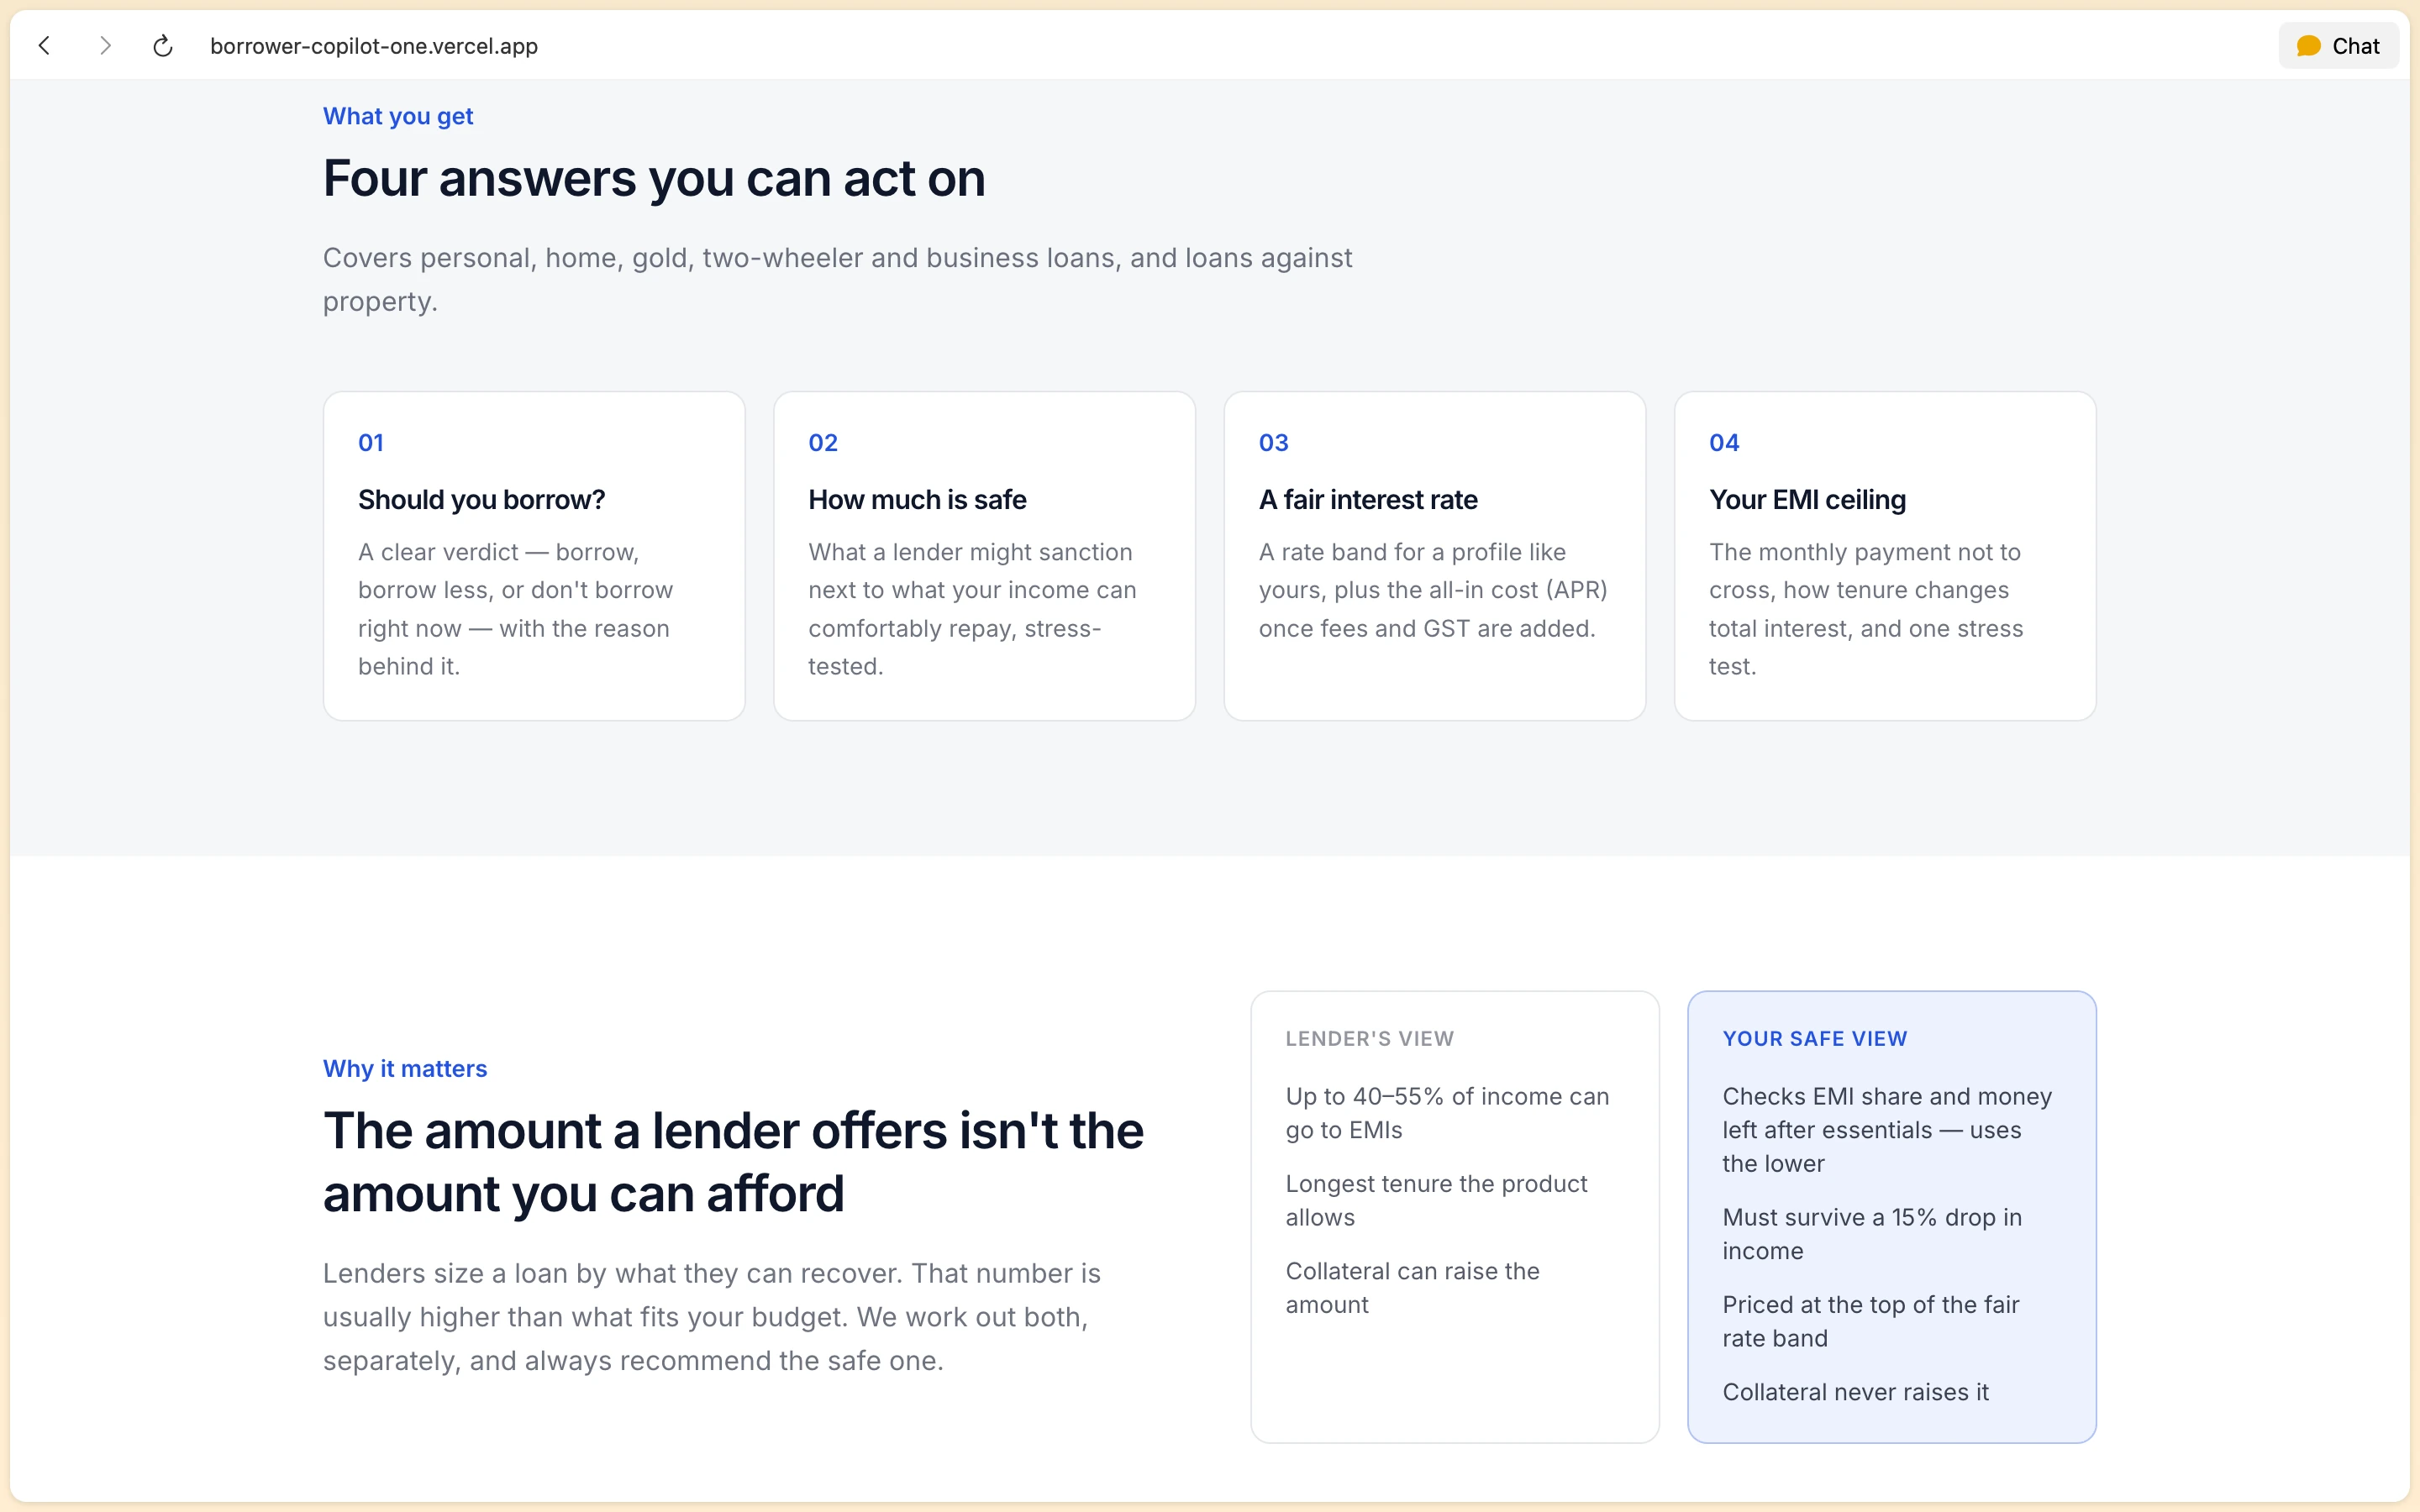
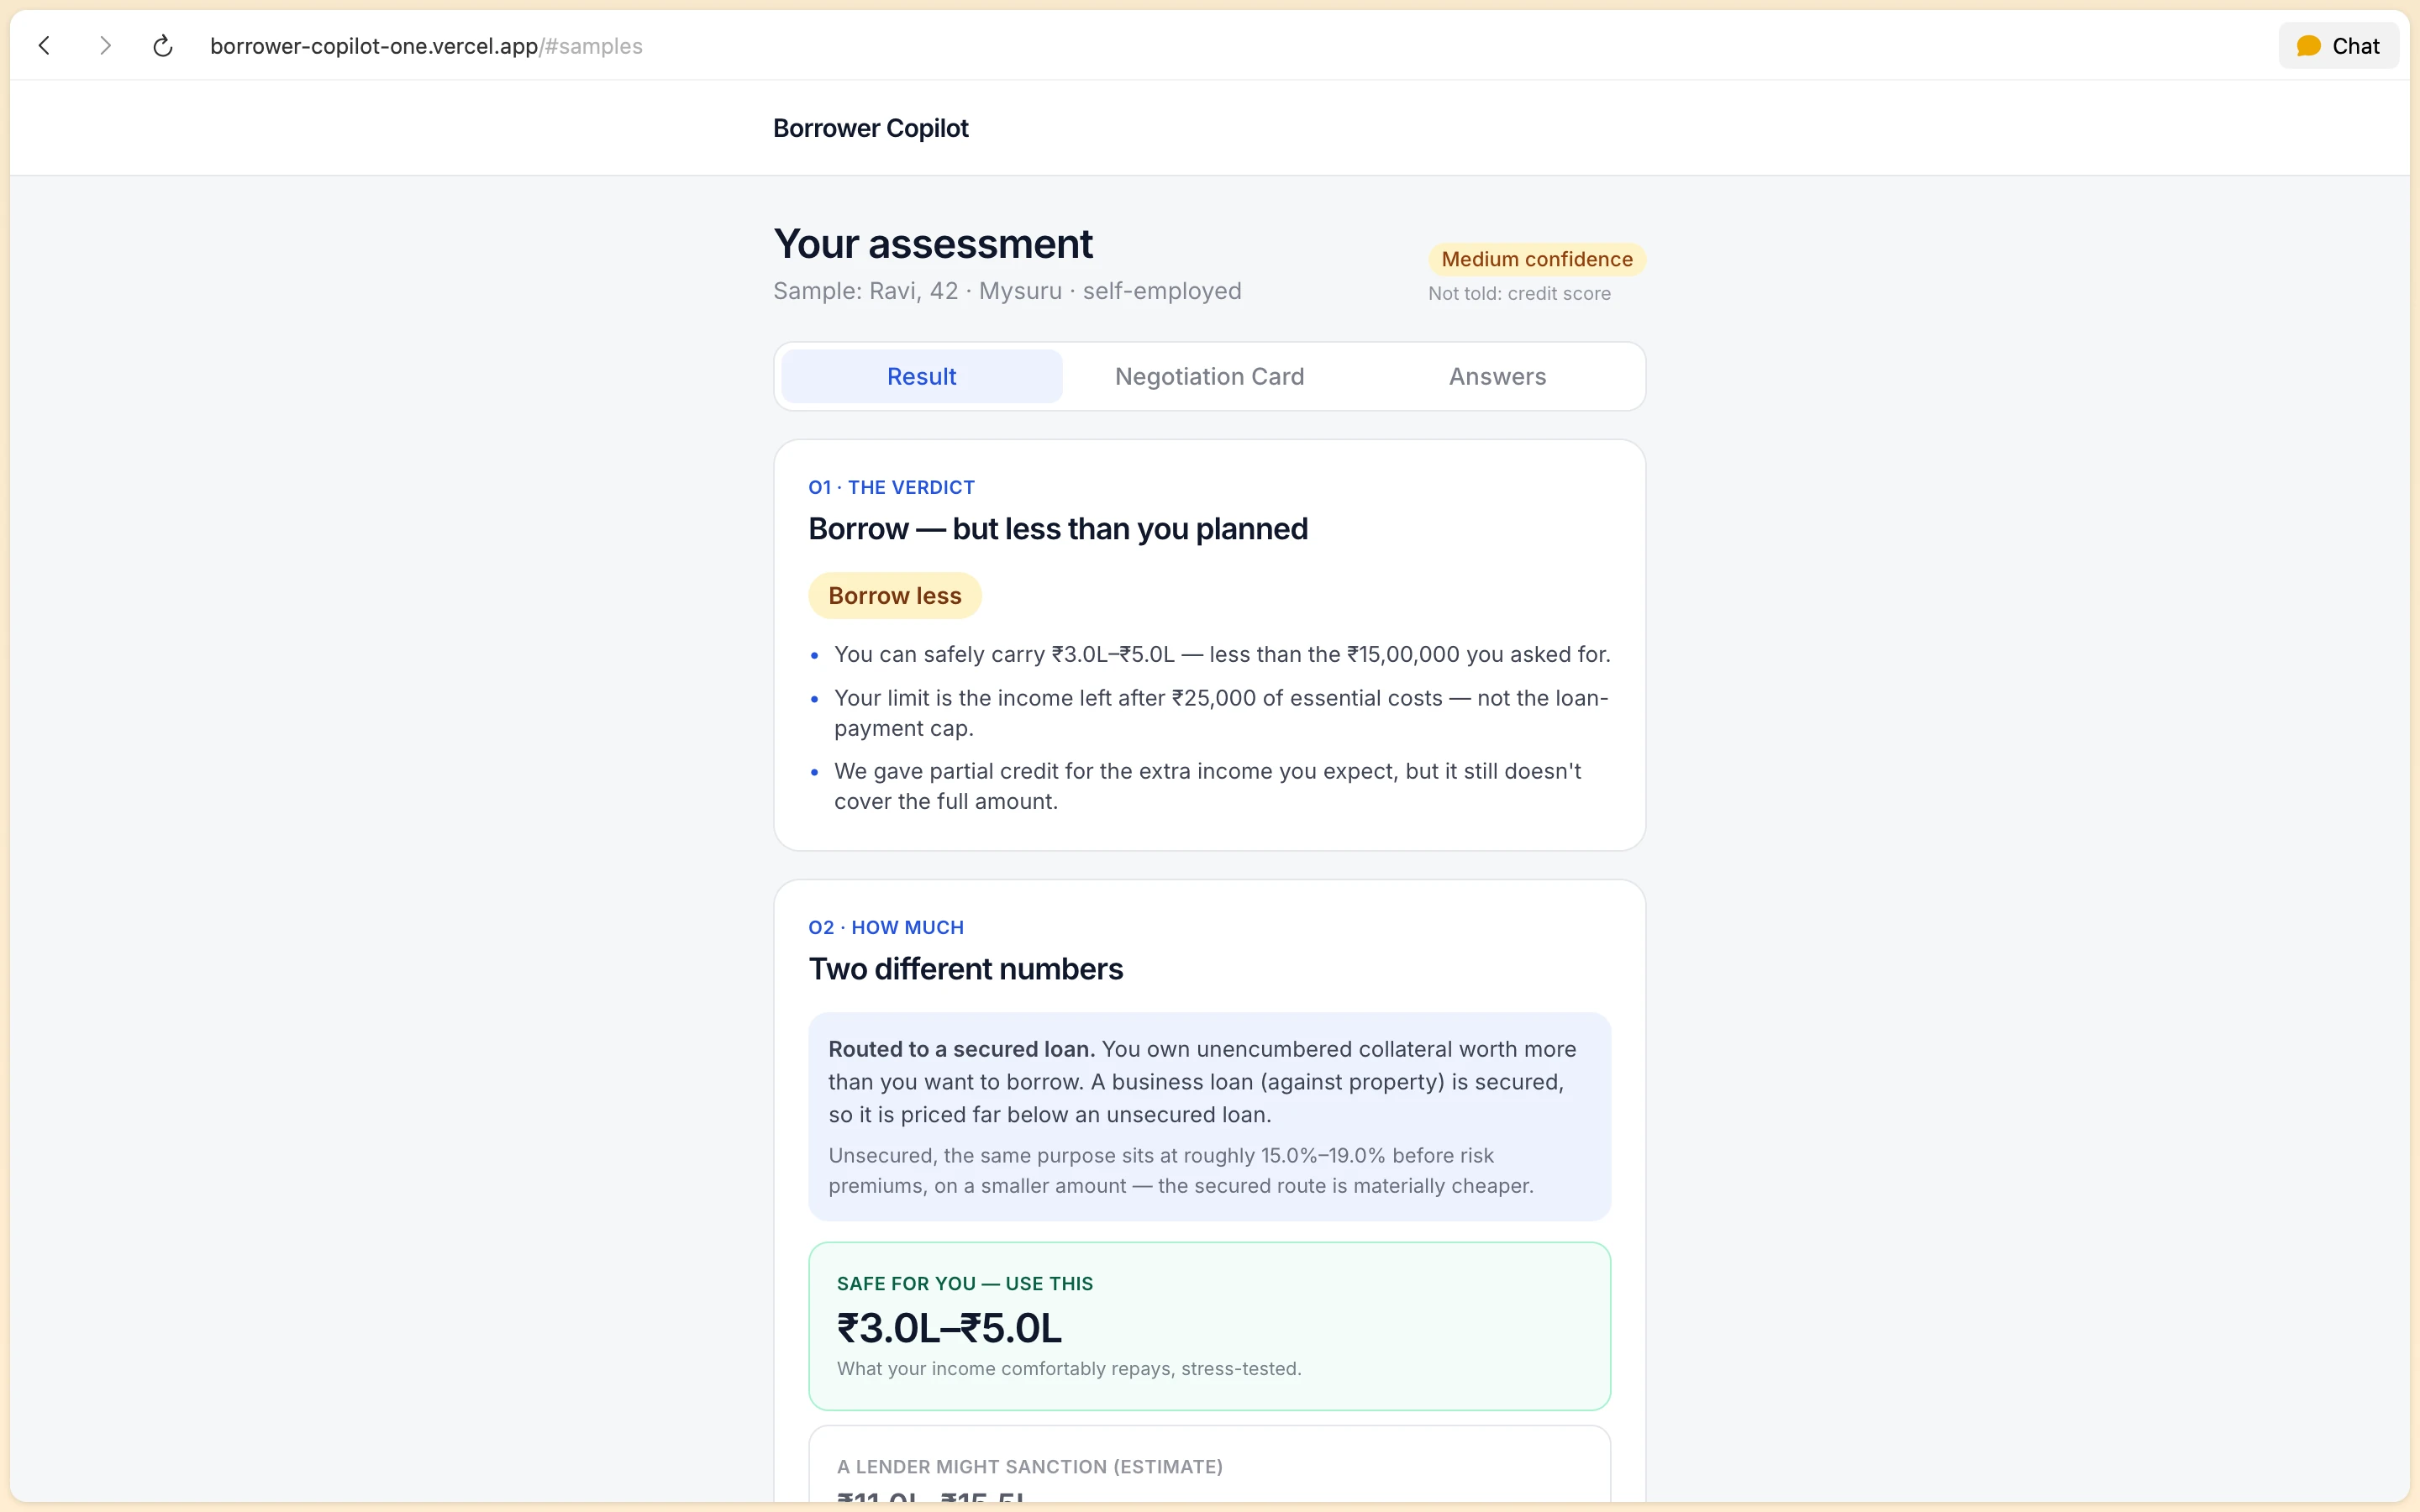
A clear verdict
Borrow, borrow less or don't borrow, with the reasons behind it.
Two different numbers
What a lender might sanction next to what your income can safely carry. The safe amount survives a 15% income drop, and collateral never raises it.
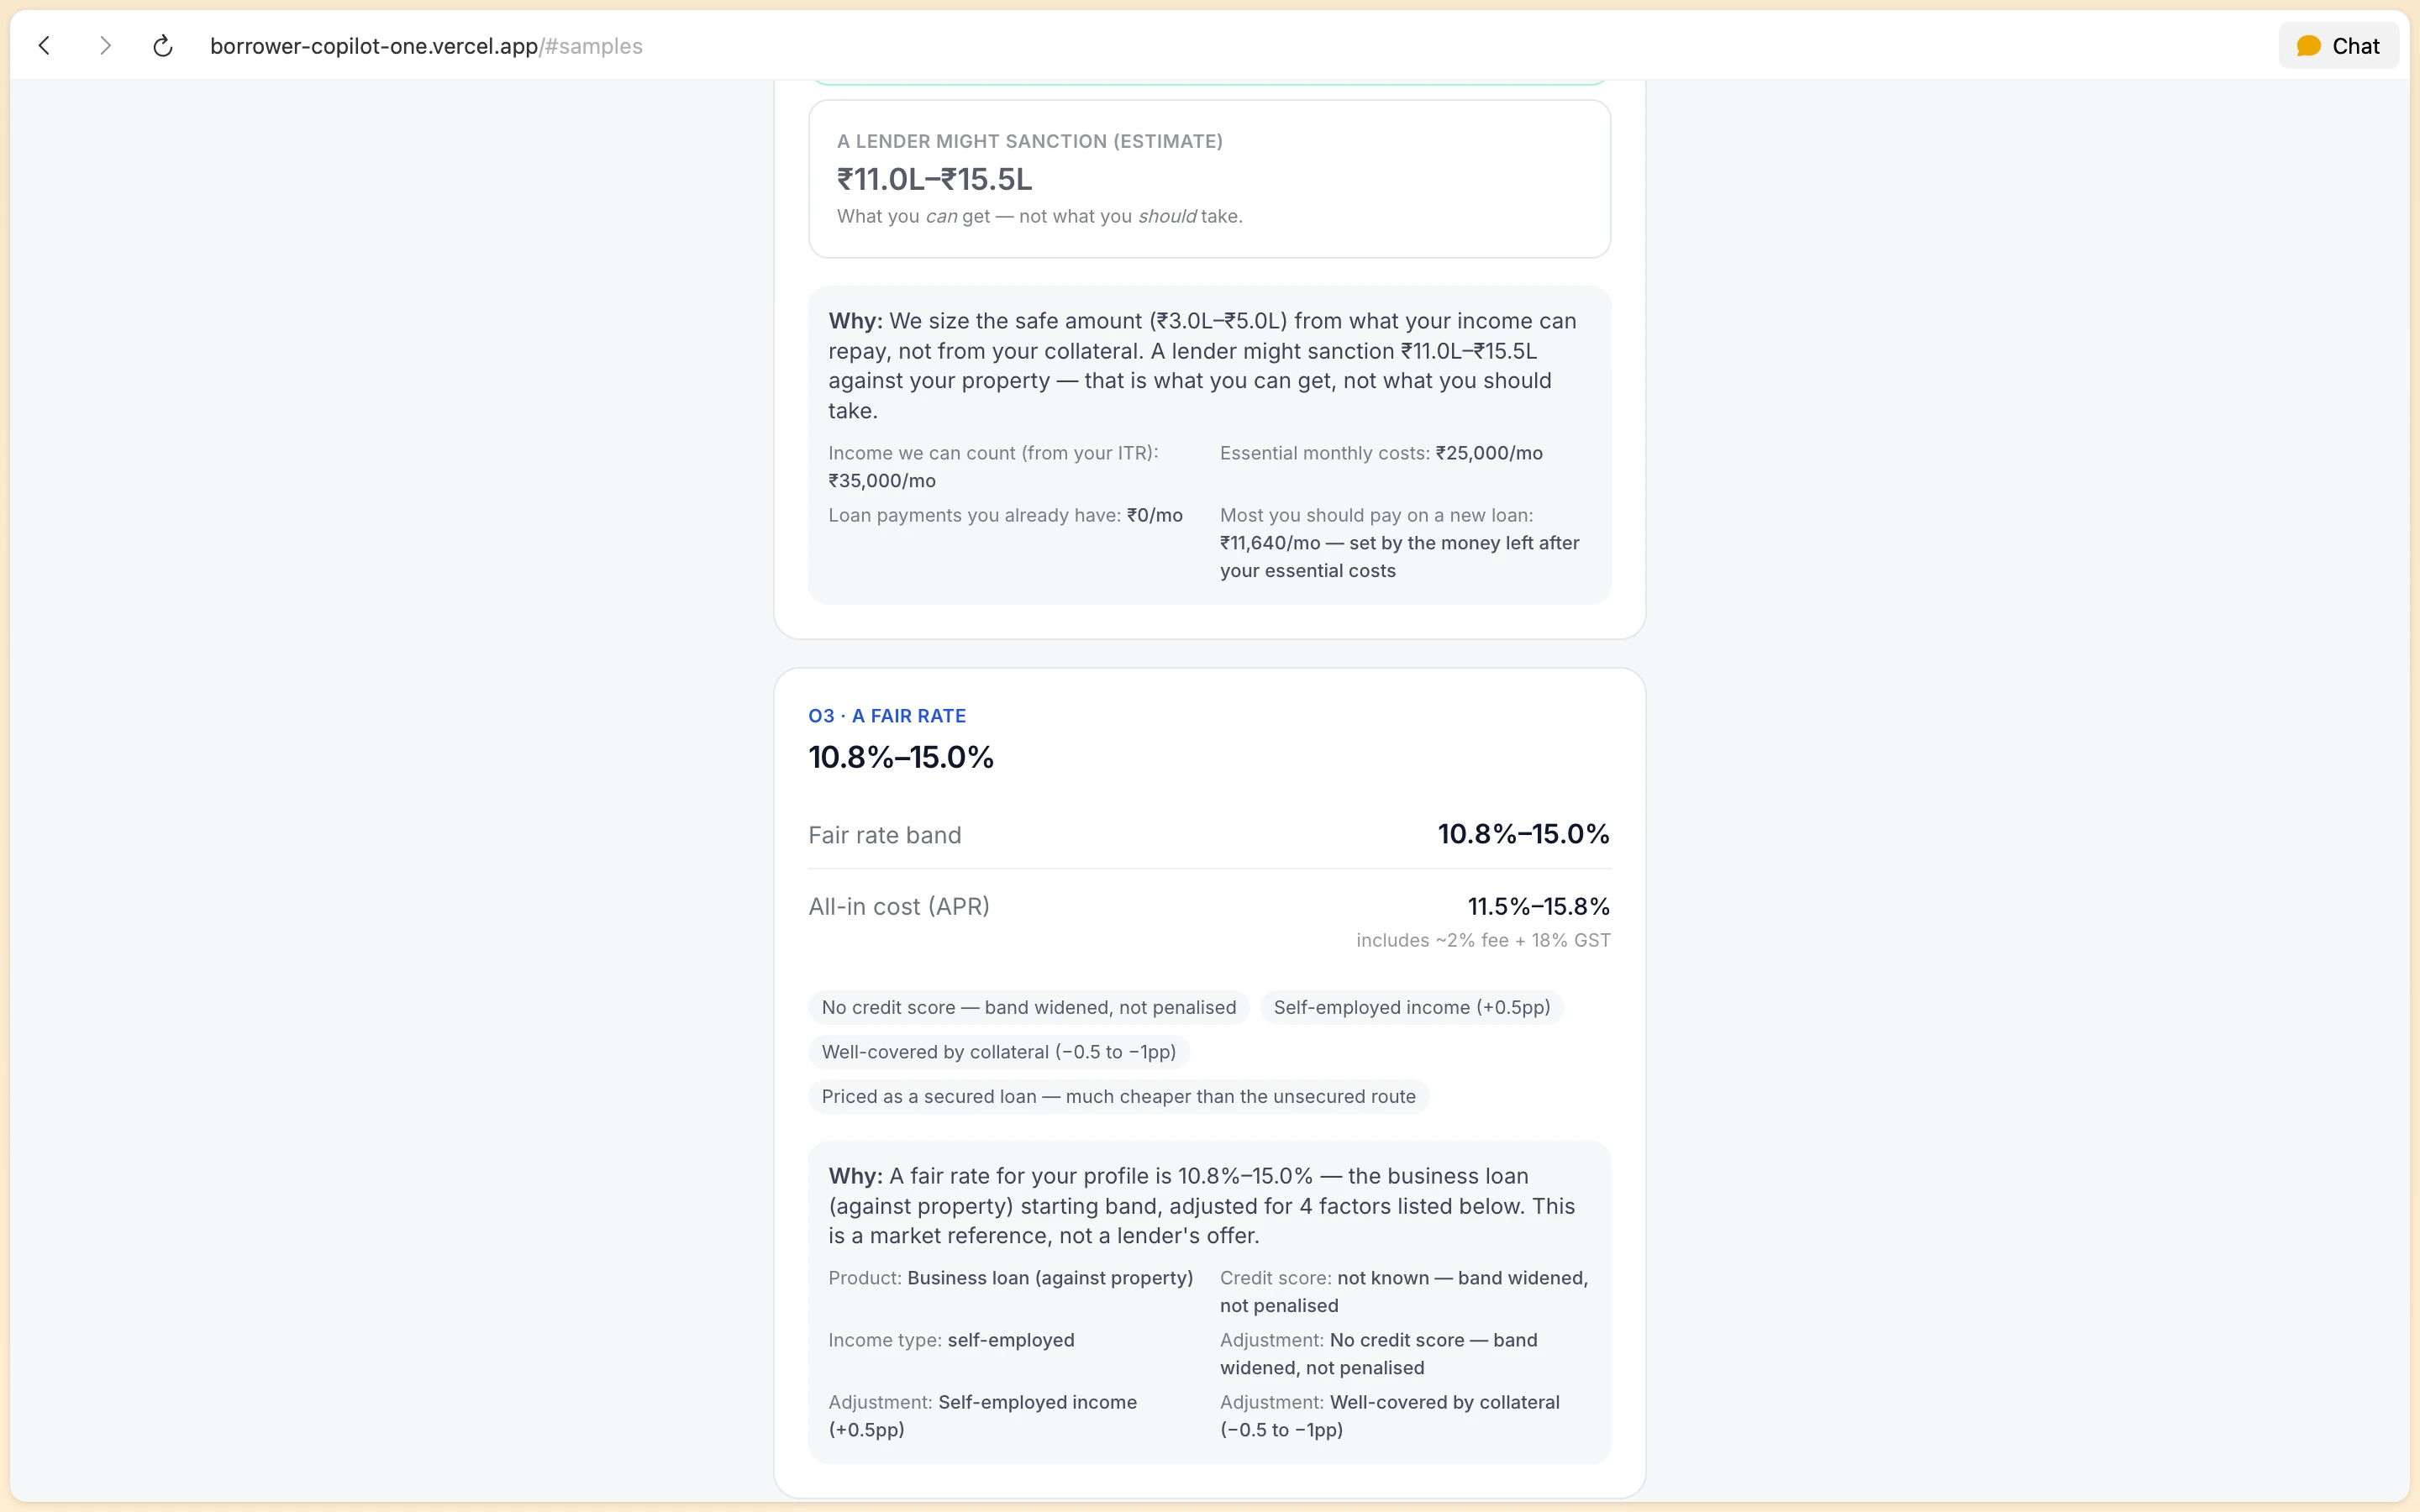
A fair rate, all in
A rate band for your profile, with each adjustment listed, plus the all-in cost (APR) once fees and GST are added.
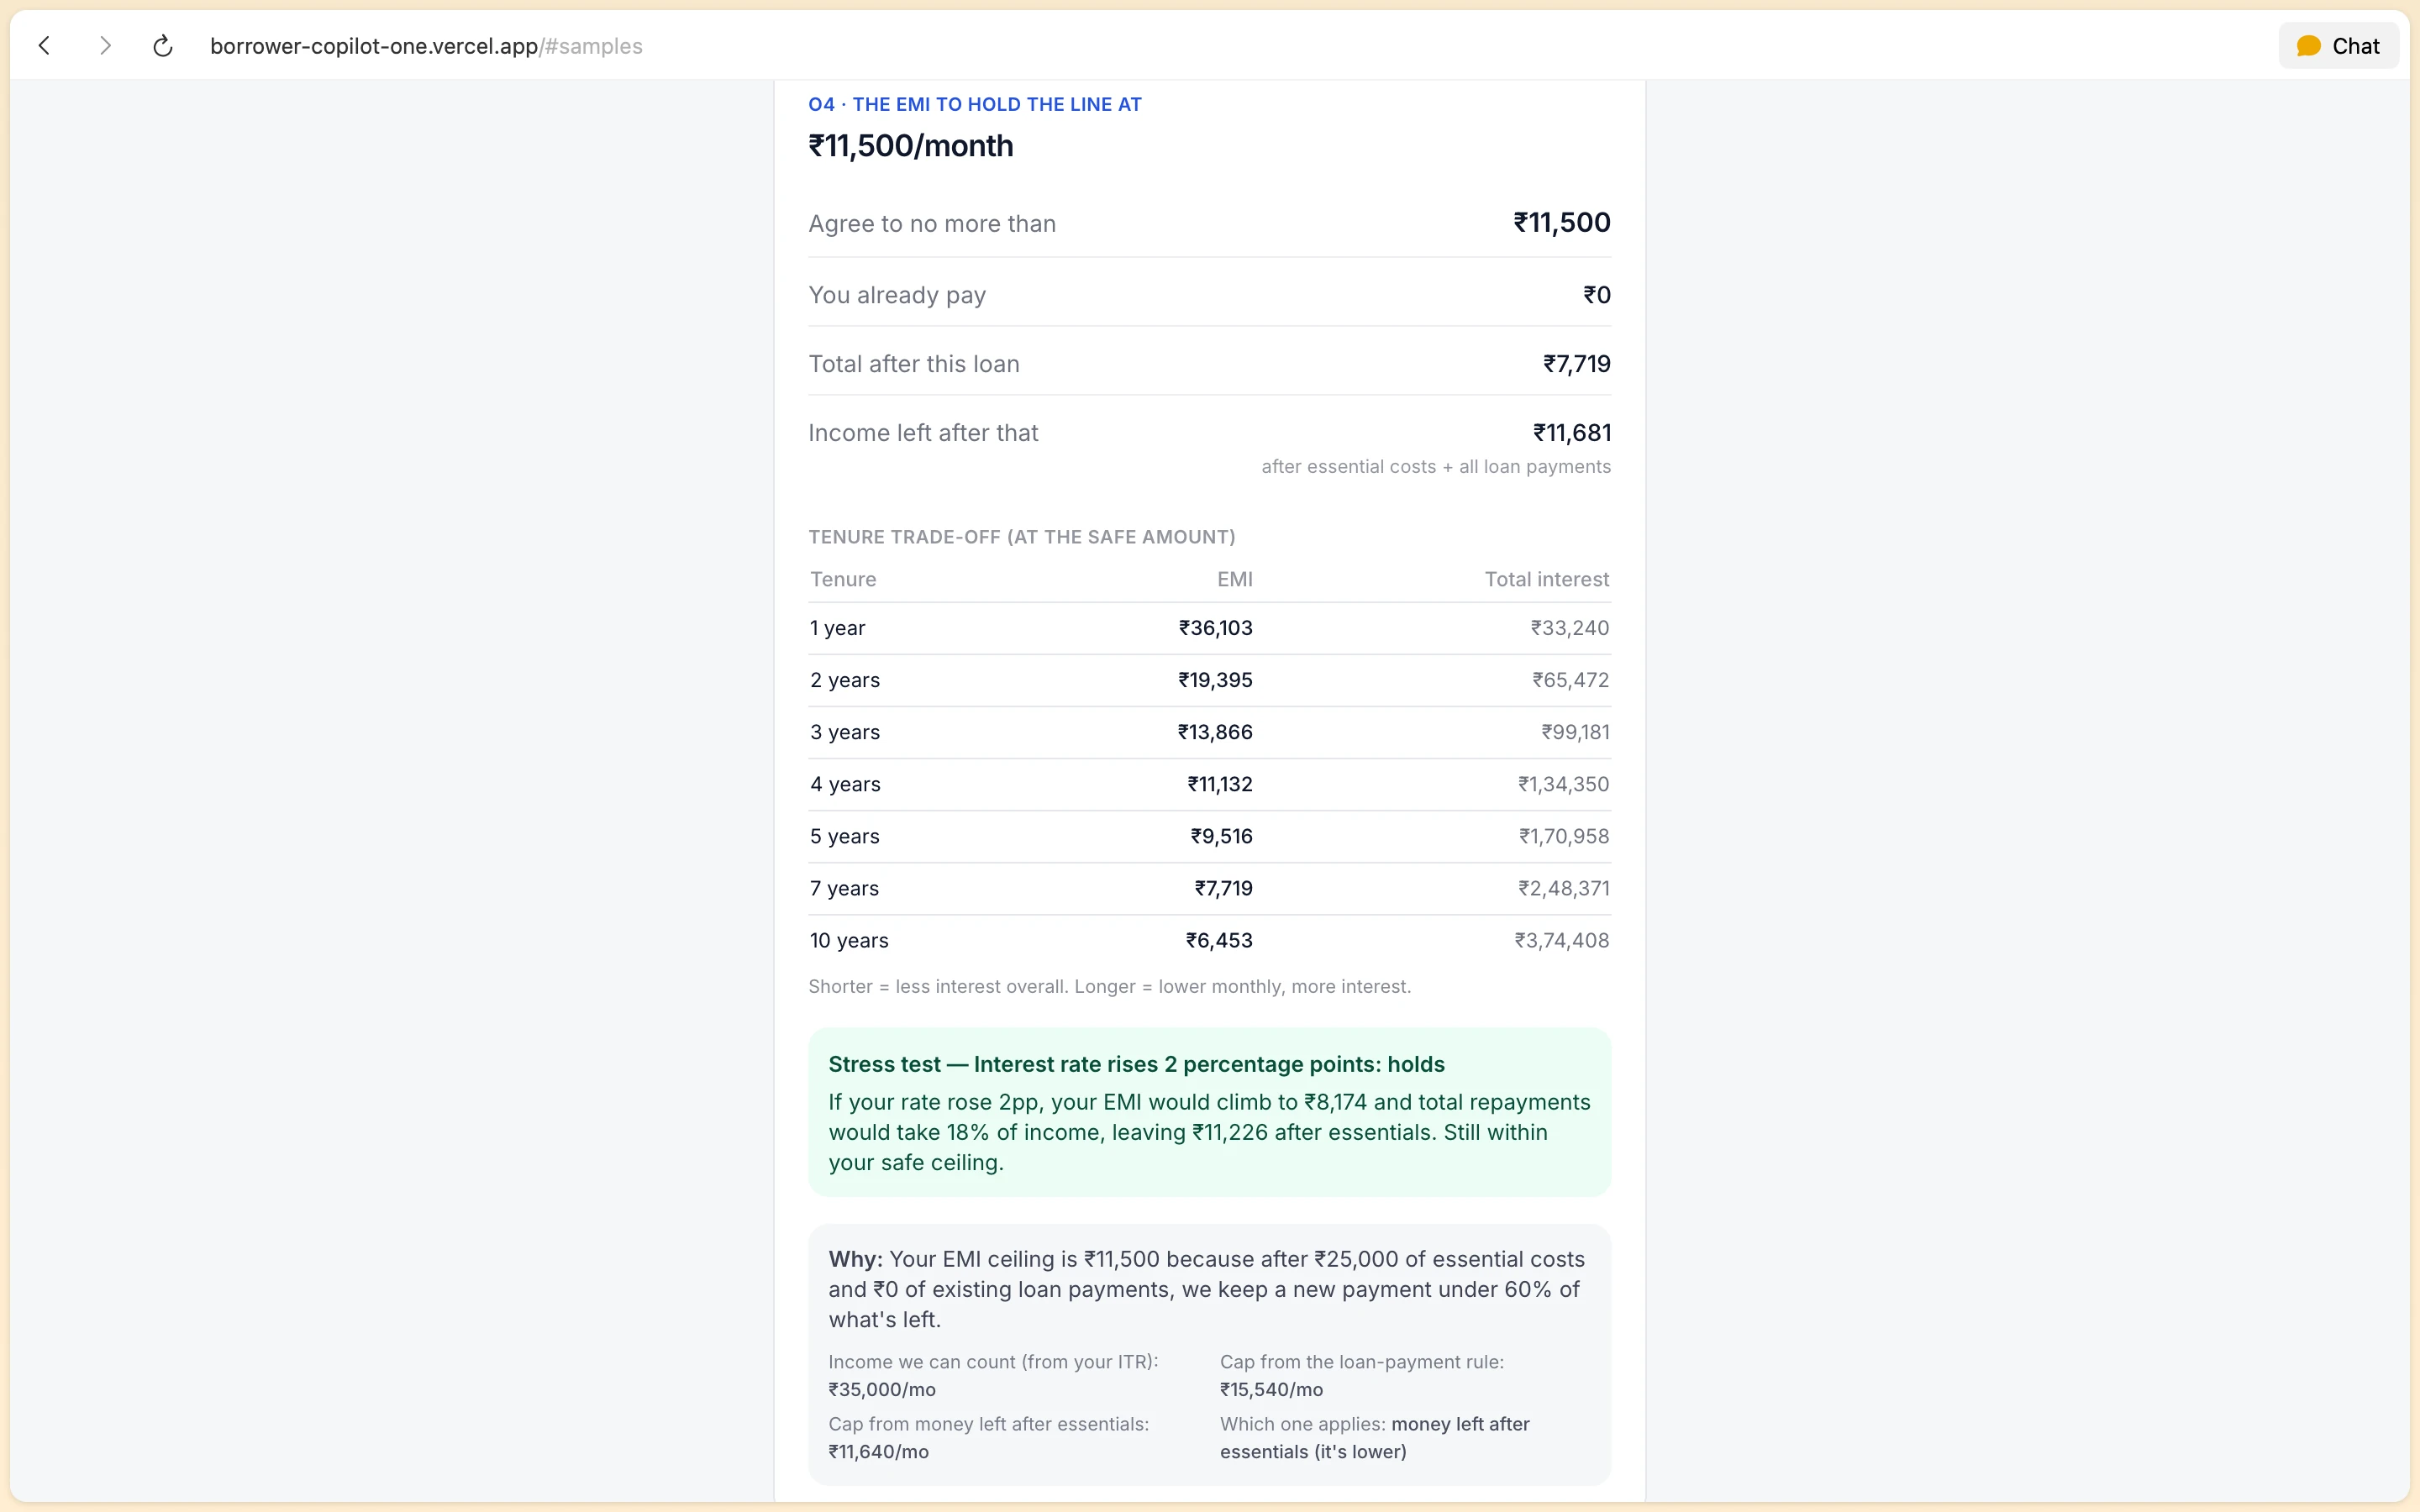
An EMI ceiling
The monthly payment not to cross, a tenure table showing total interest, and one stress test.
Honest about gaps
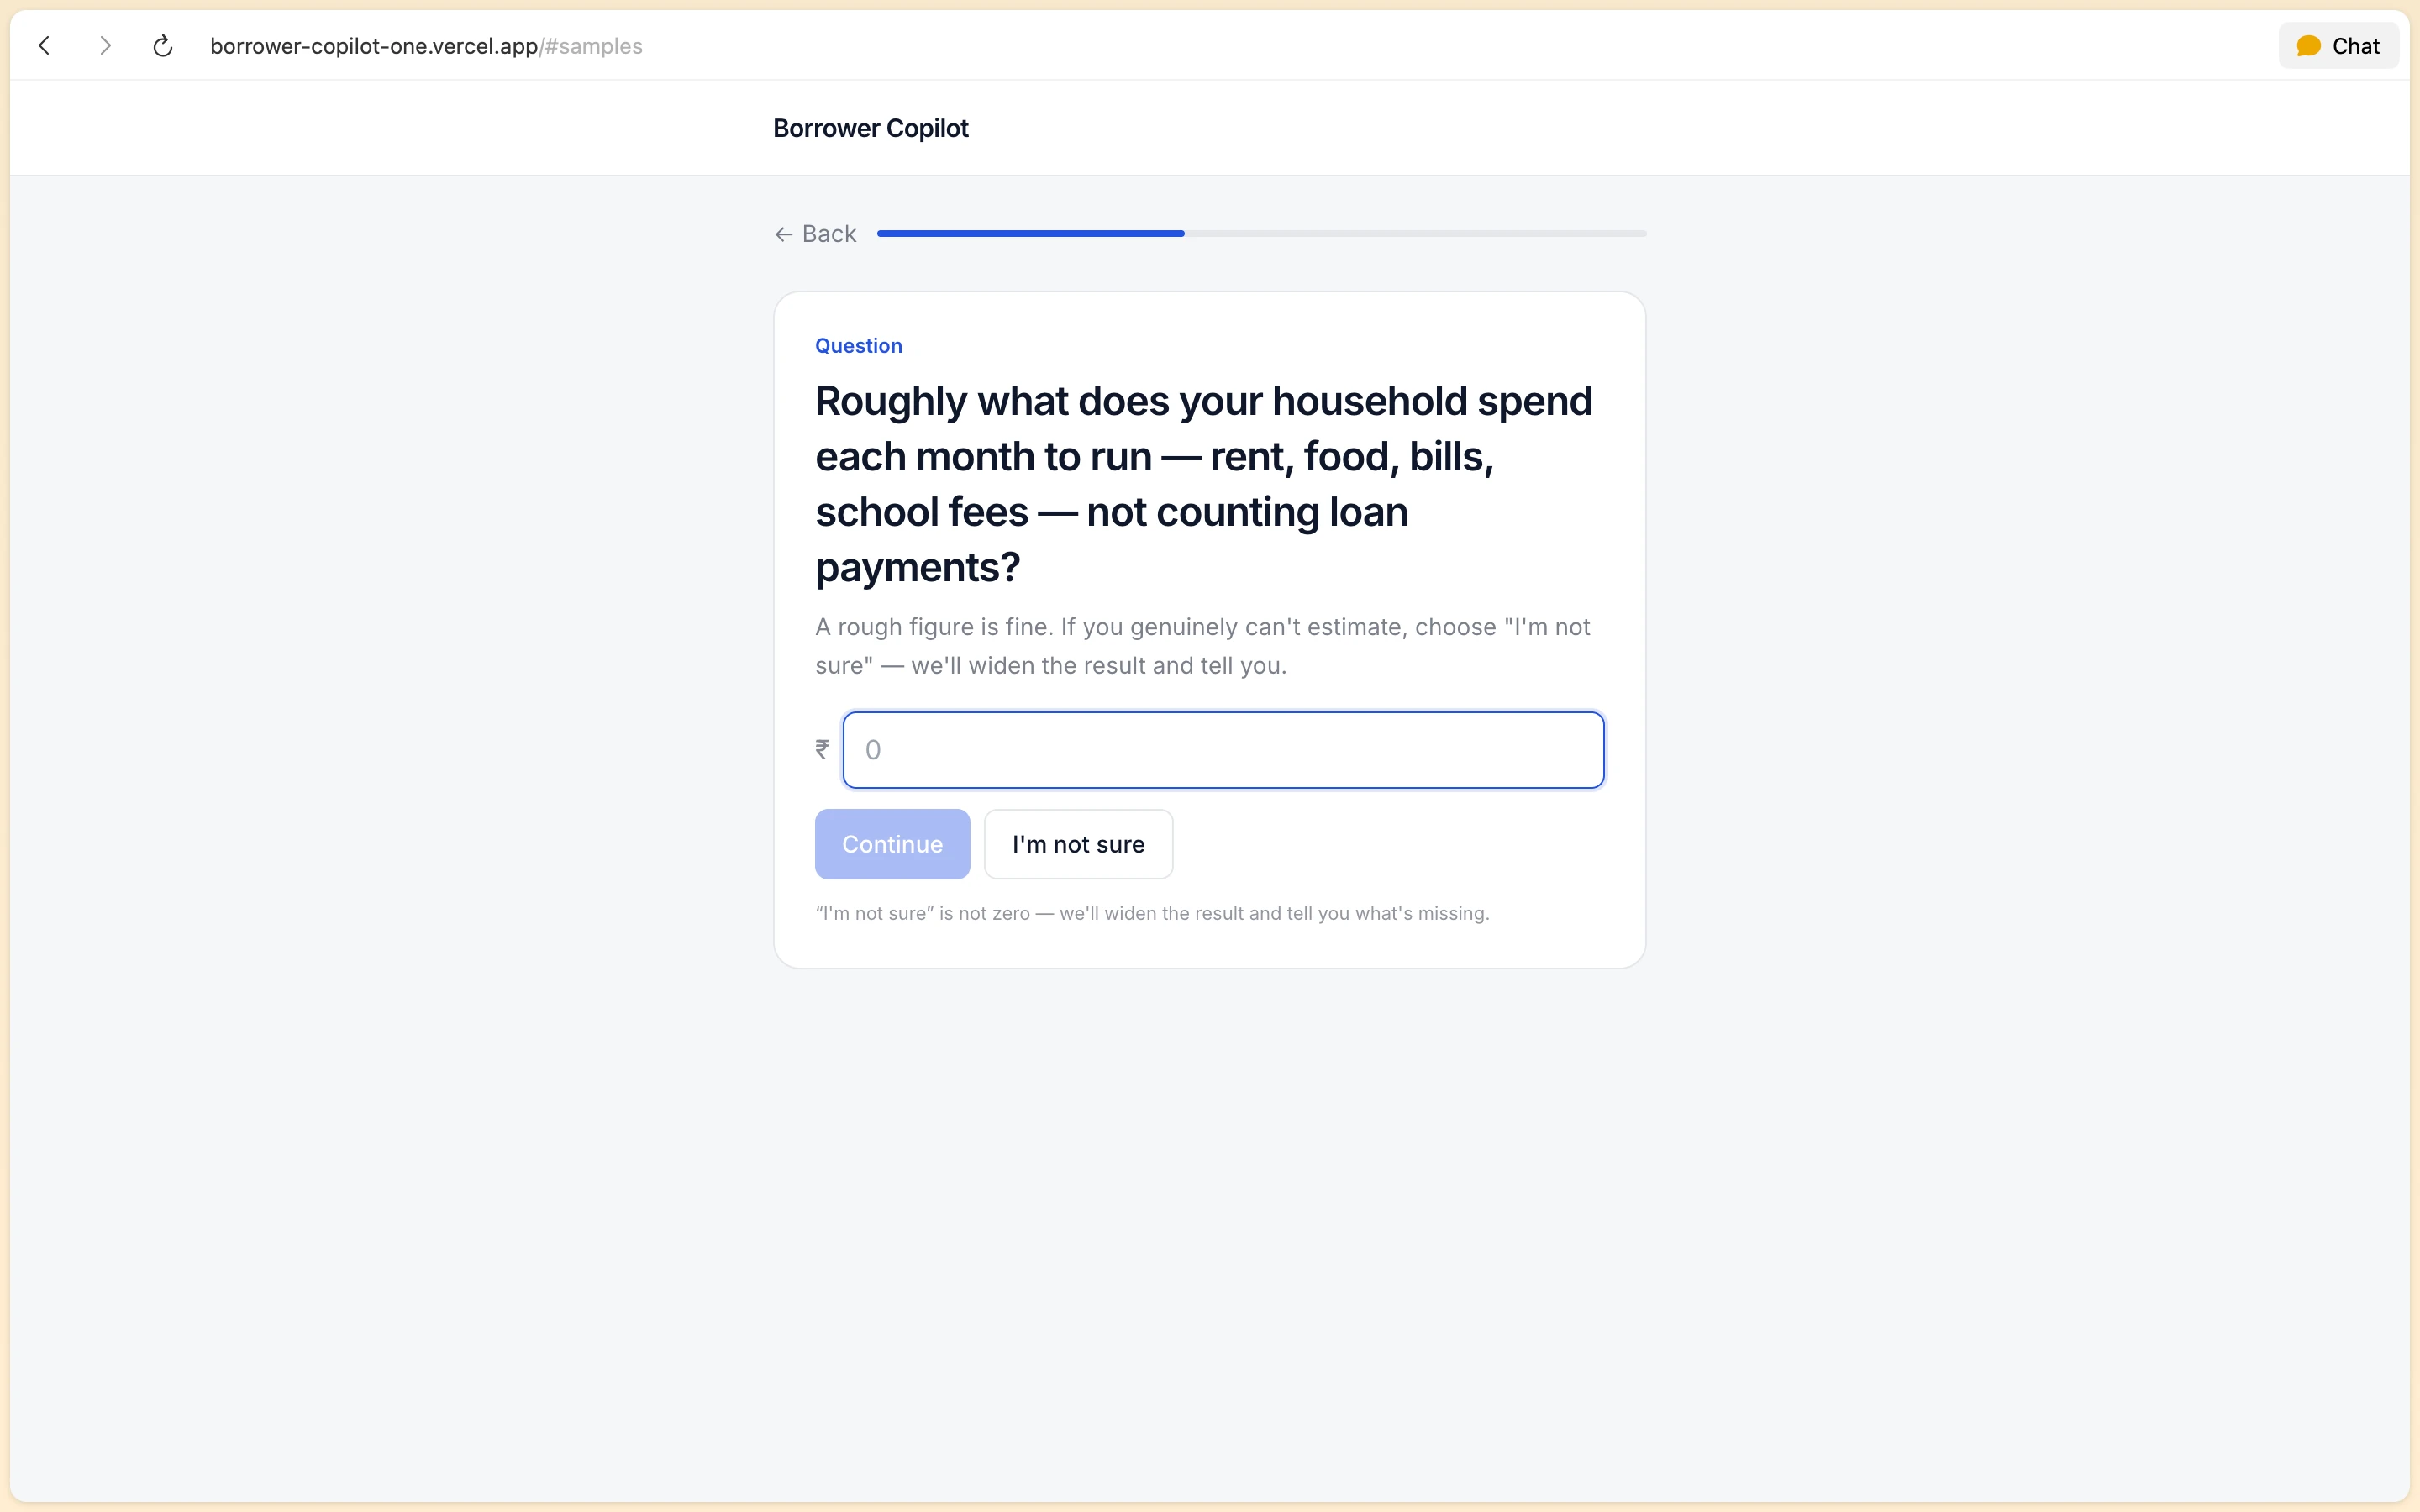
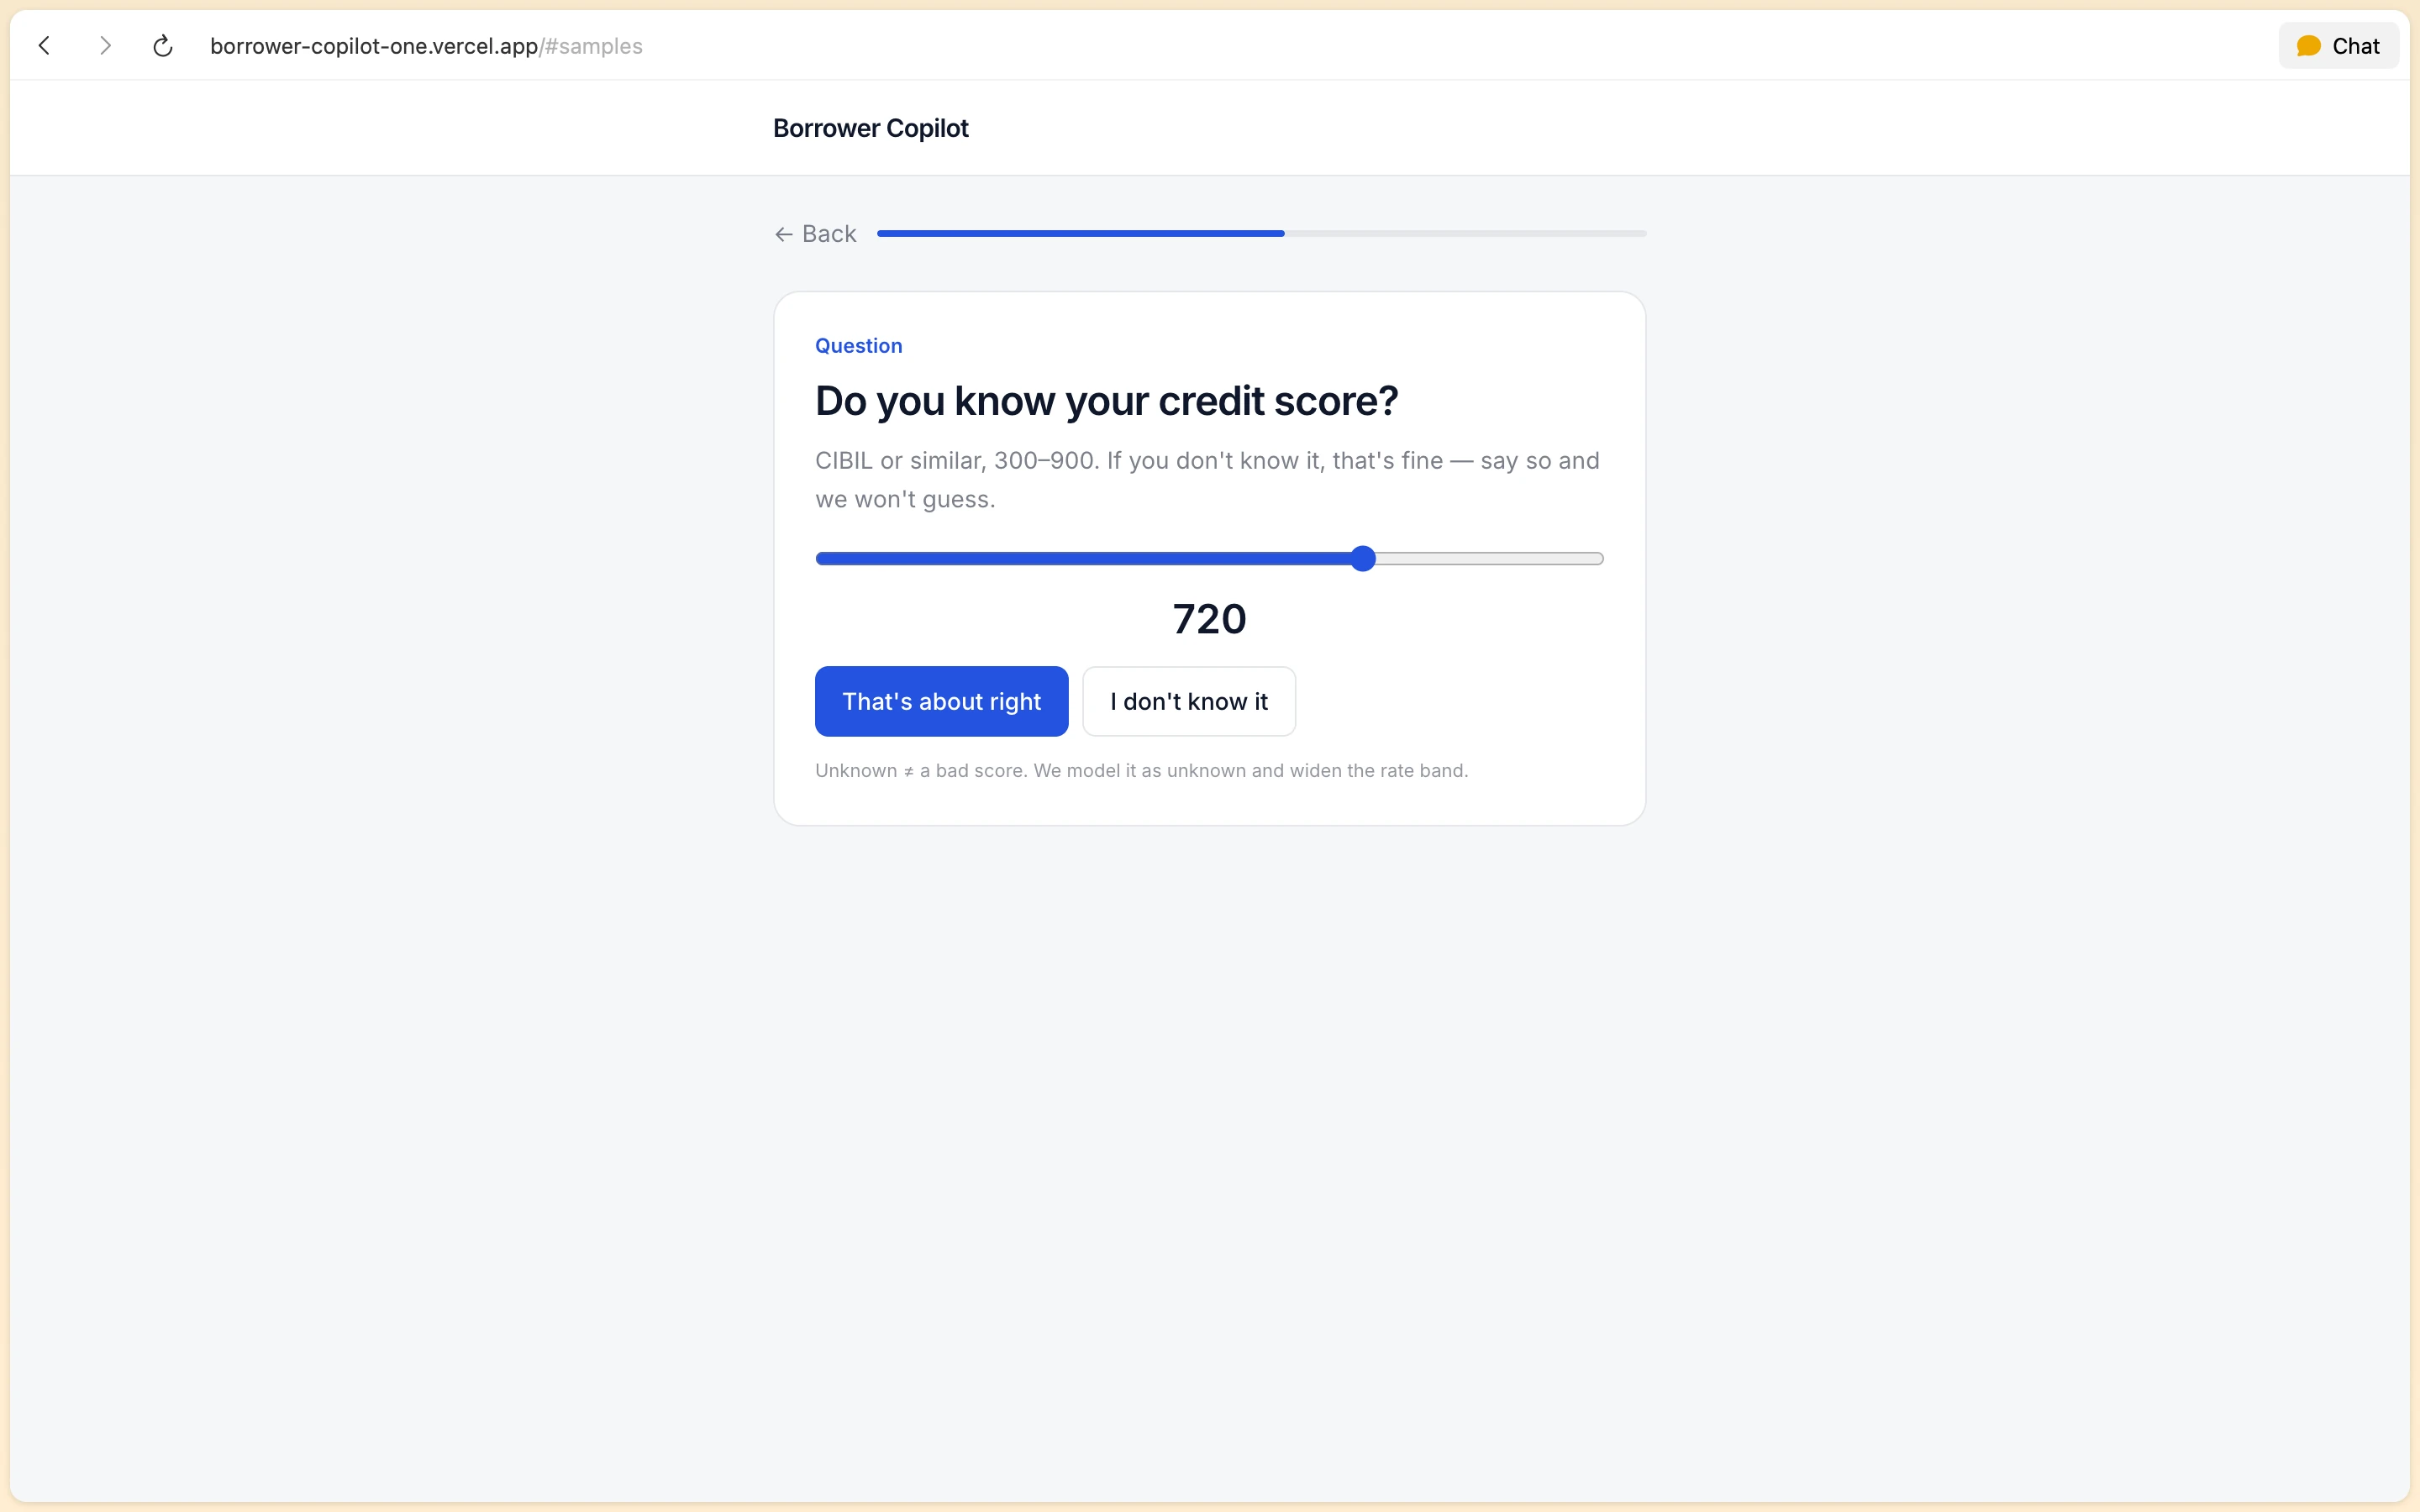
“I'm not sure” is never treated as zero. Skipped answers lower the confidence and widen the ranges instead.
Negotiation Card
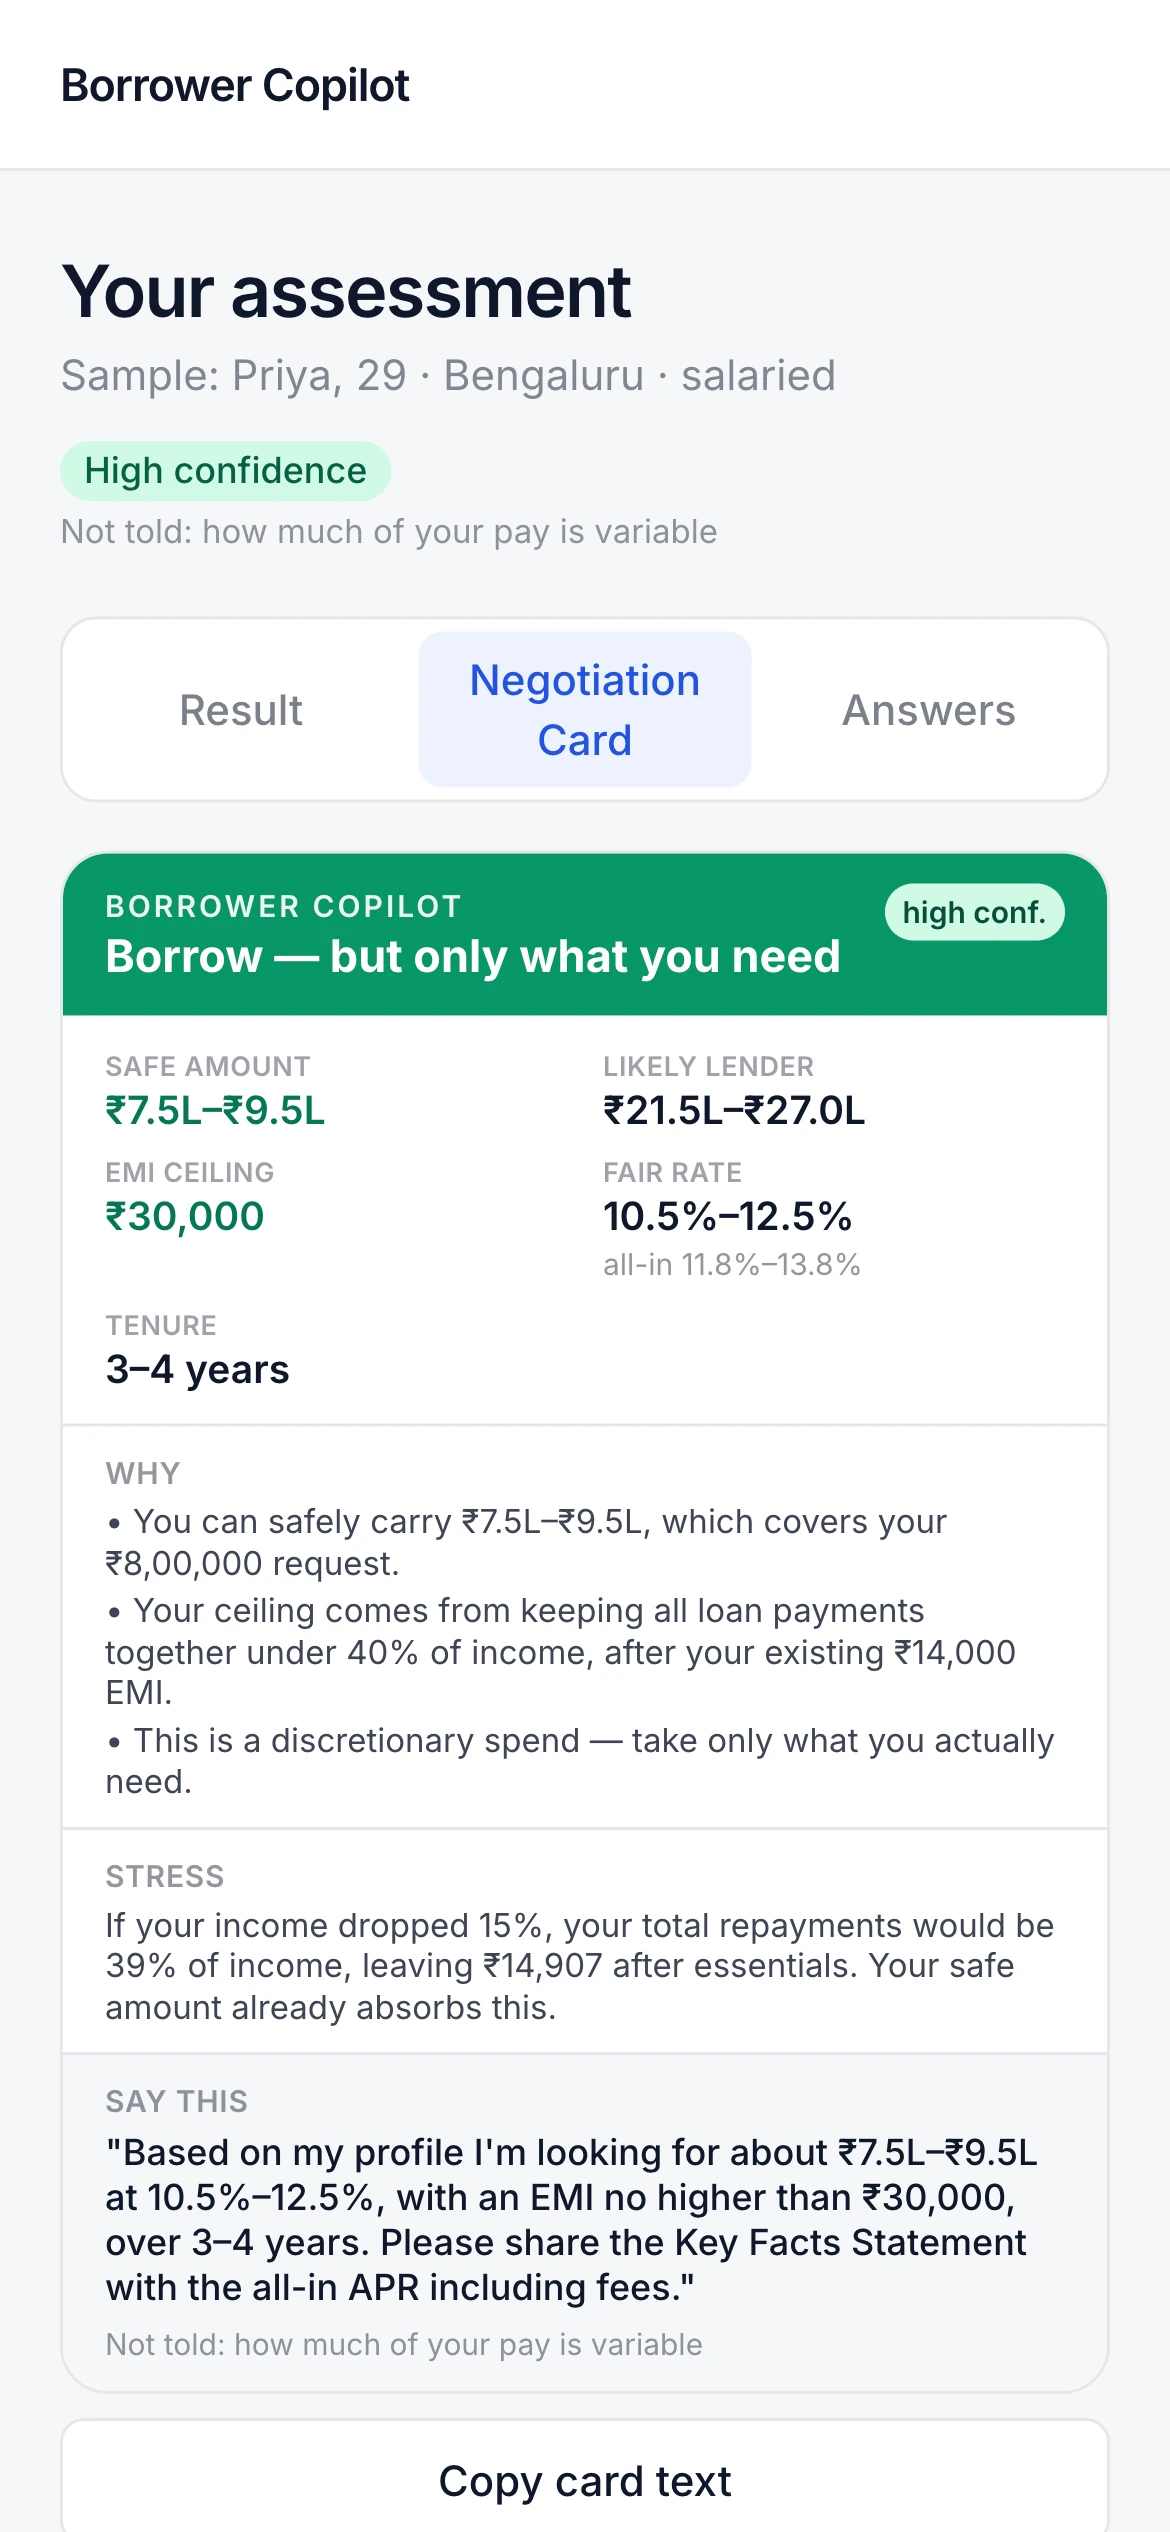
A one-screen summary with the amount, rate, EMI and tenure to ask for, ready to screenshot or copy before visiting a lender.
Under the hood
How it works
The part nobody sees, step by step.
Ask
A question engine picks the next question from 9 core and 14 adaptive ones, based on the answers so far.
Derive
Answers become stable income, essential costs, a credit tier and a product route, with unknowns kept separate from zeros.
Compute
Pure functions work out the confidence, the rate band and APR, the safe EMI, the safe amount, the lender's estimate and a stress test.
Explain
Each output gets a one-sentence reason built from the numbers actually used, and the results become the Negotiation Card.
Screens
Every screen, as shipped
Captured from the live product at borrower-copilot-one.vercel.app.
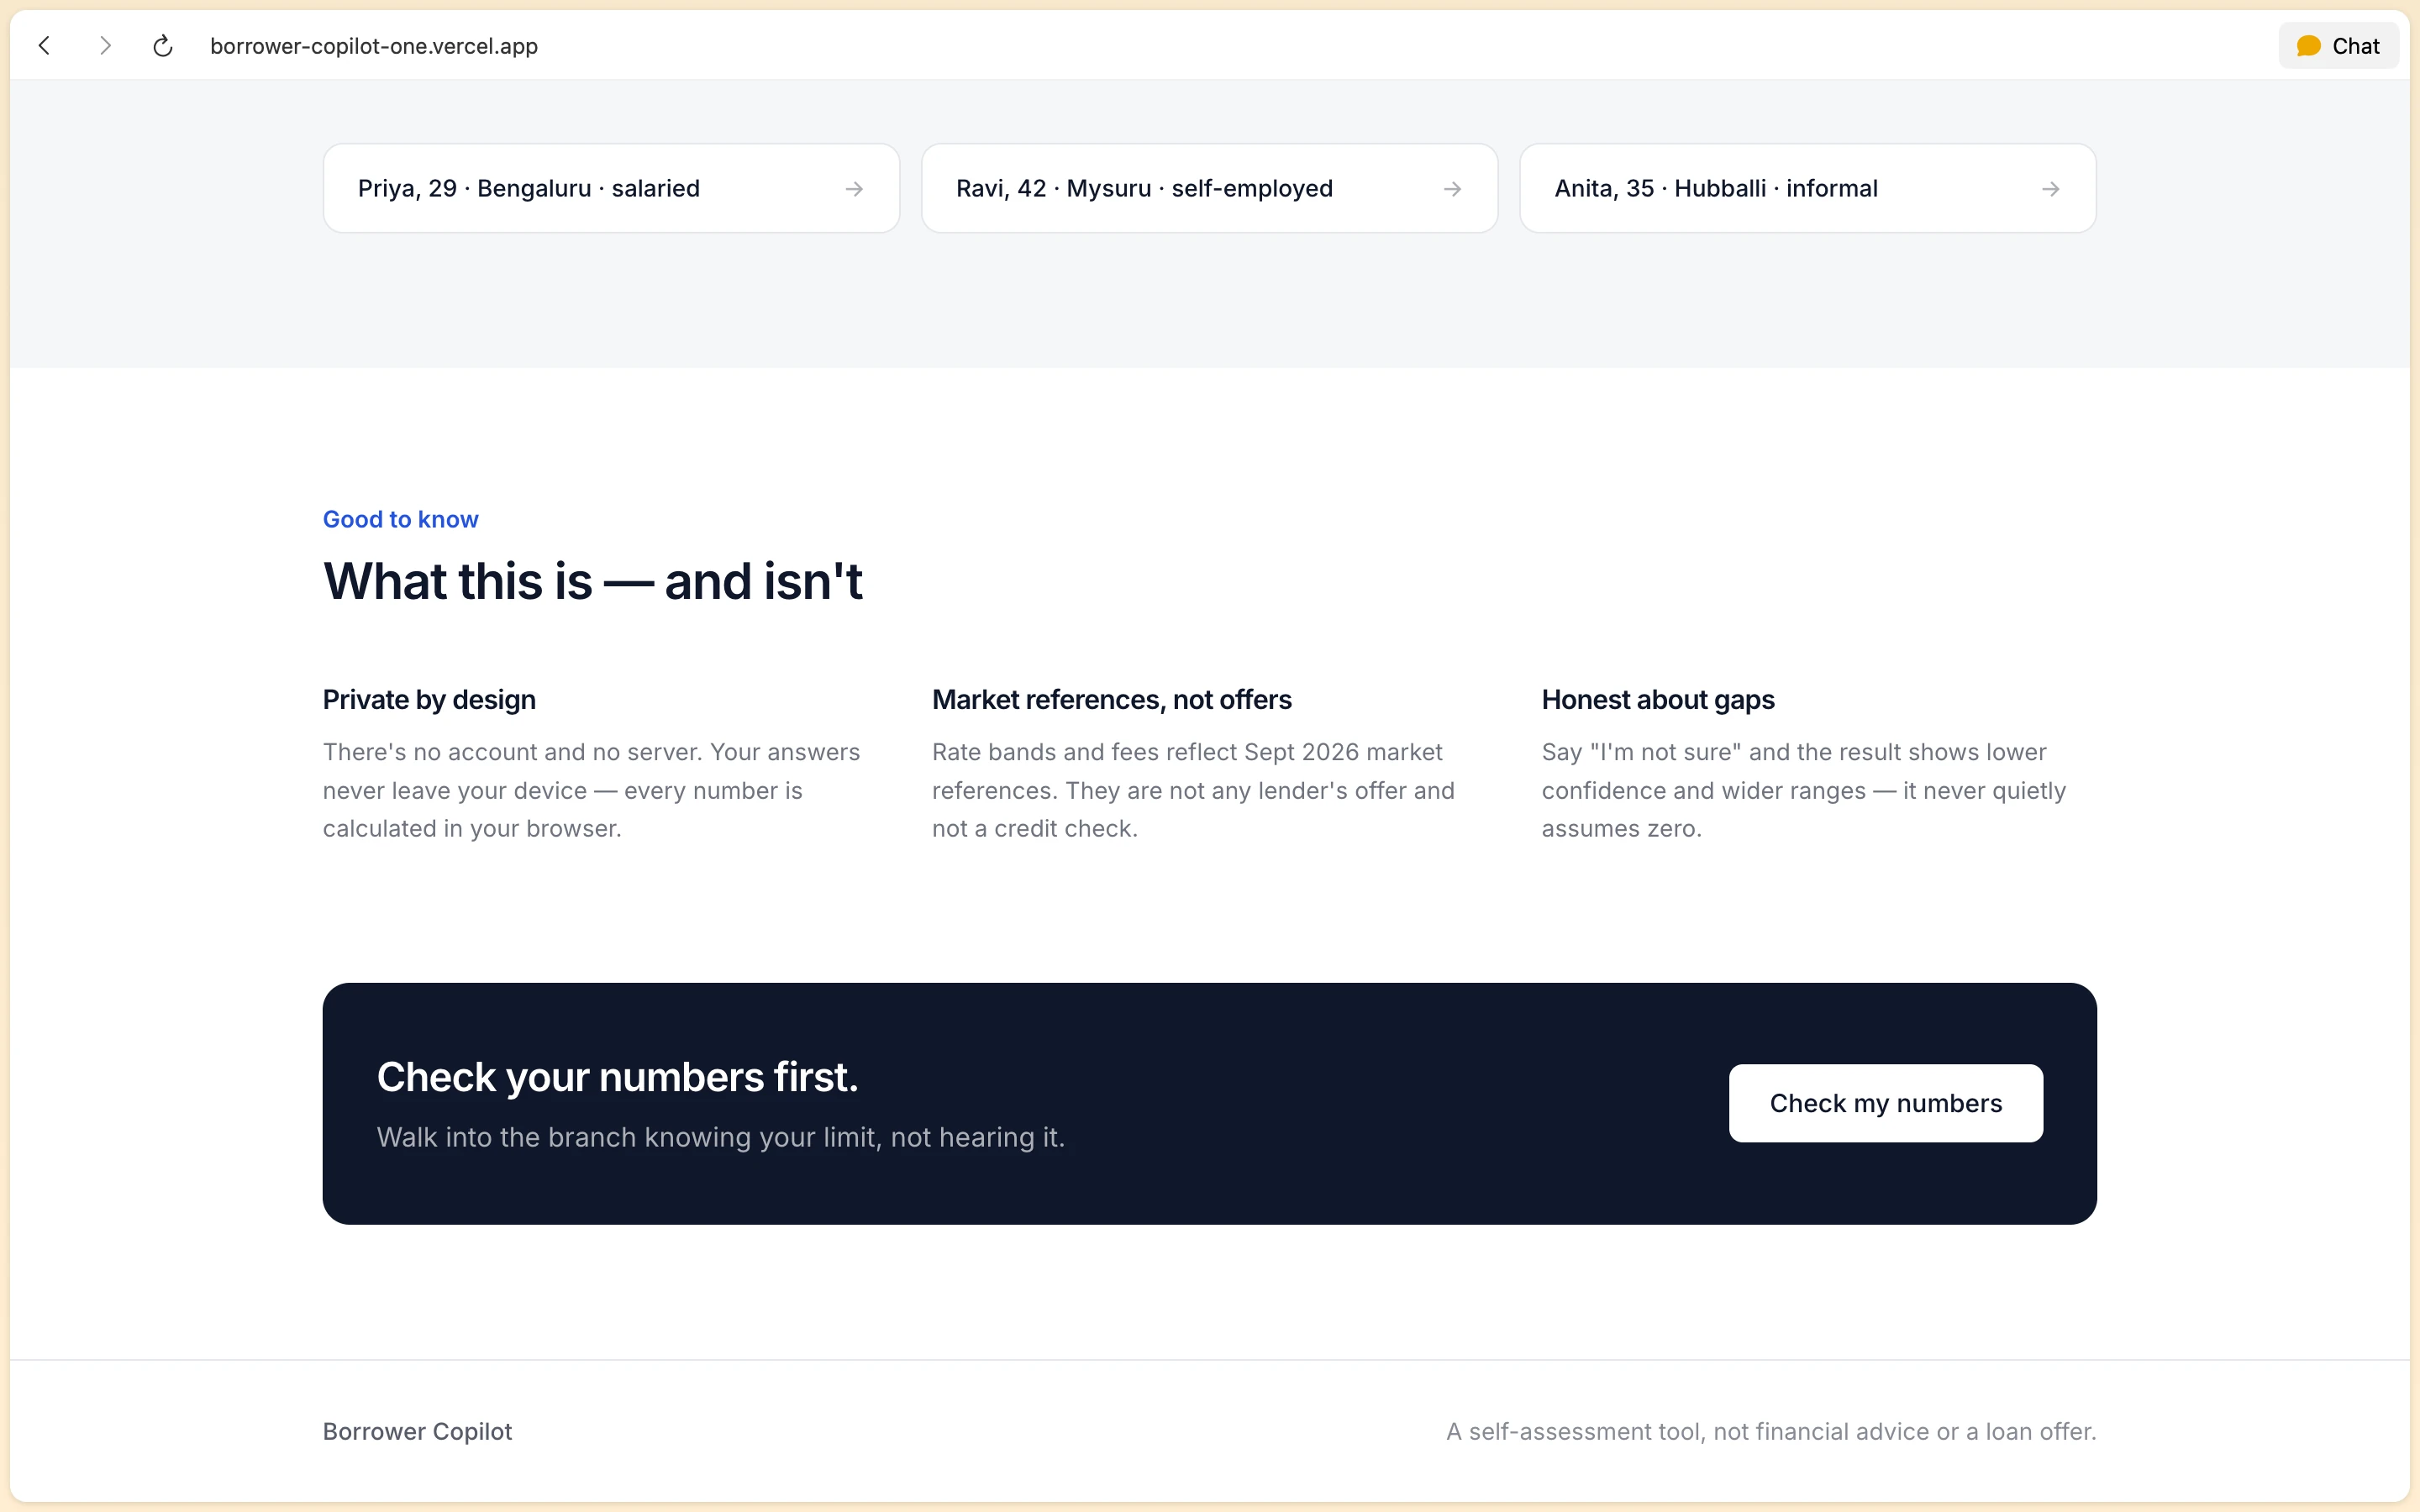
The site
What you get, how it works, sample borrowers to try, and what the tool is and isn't.
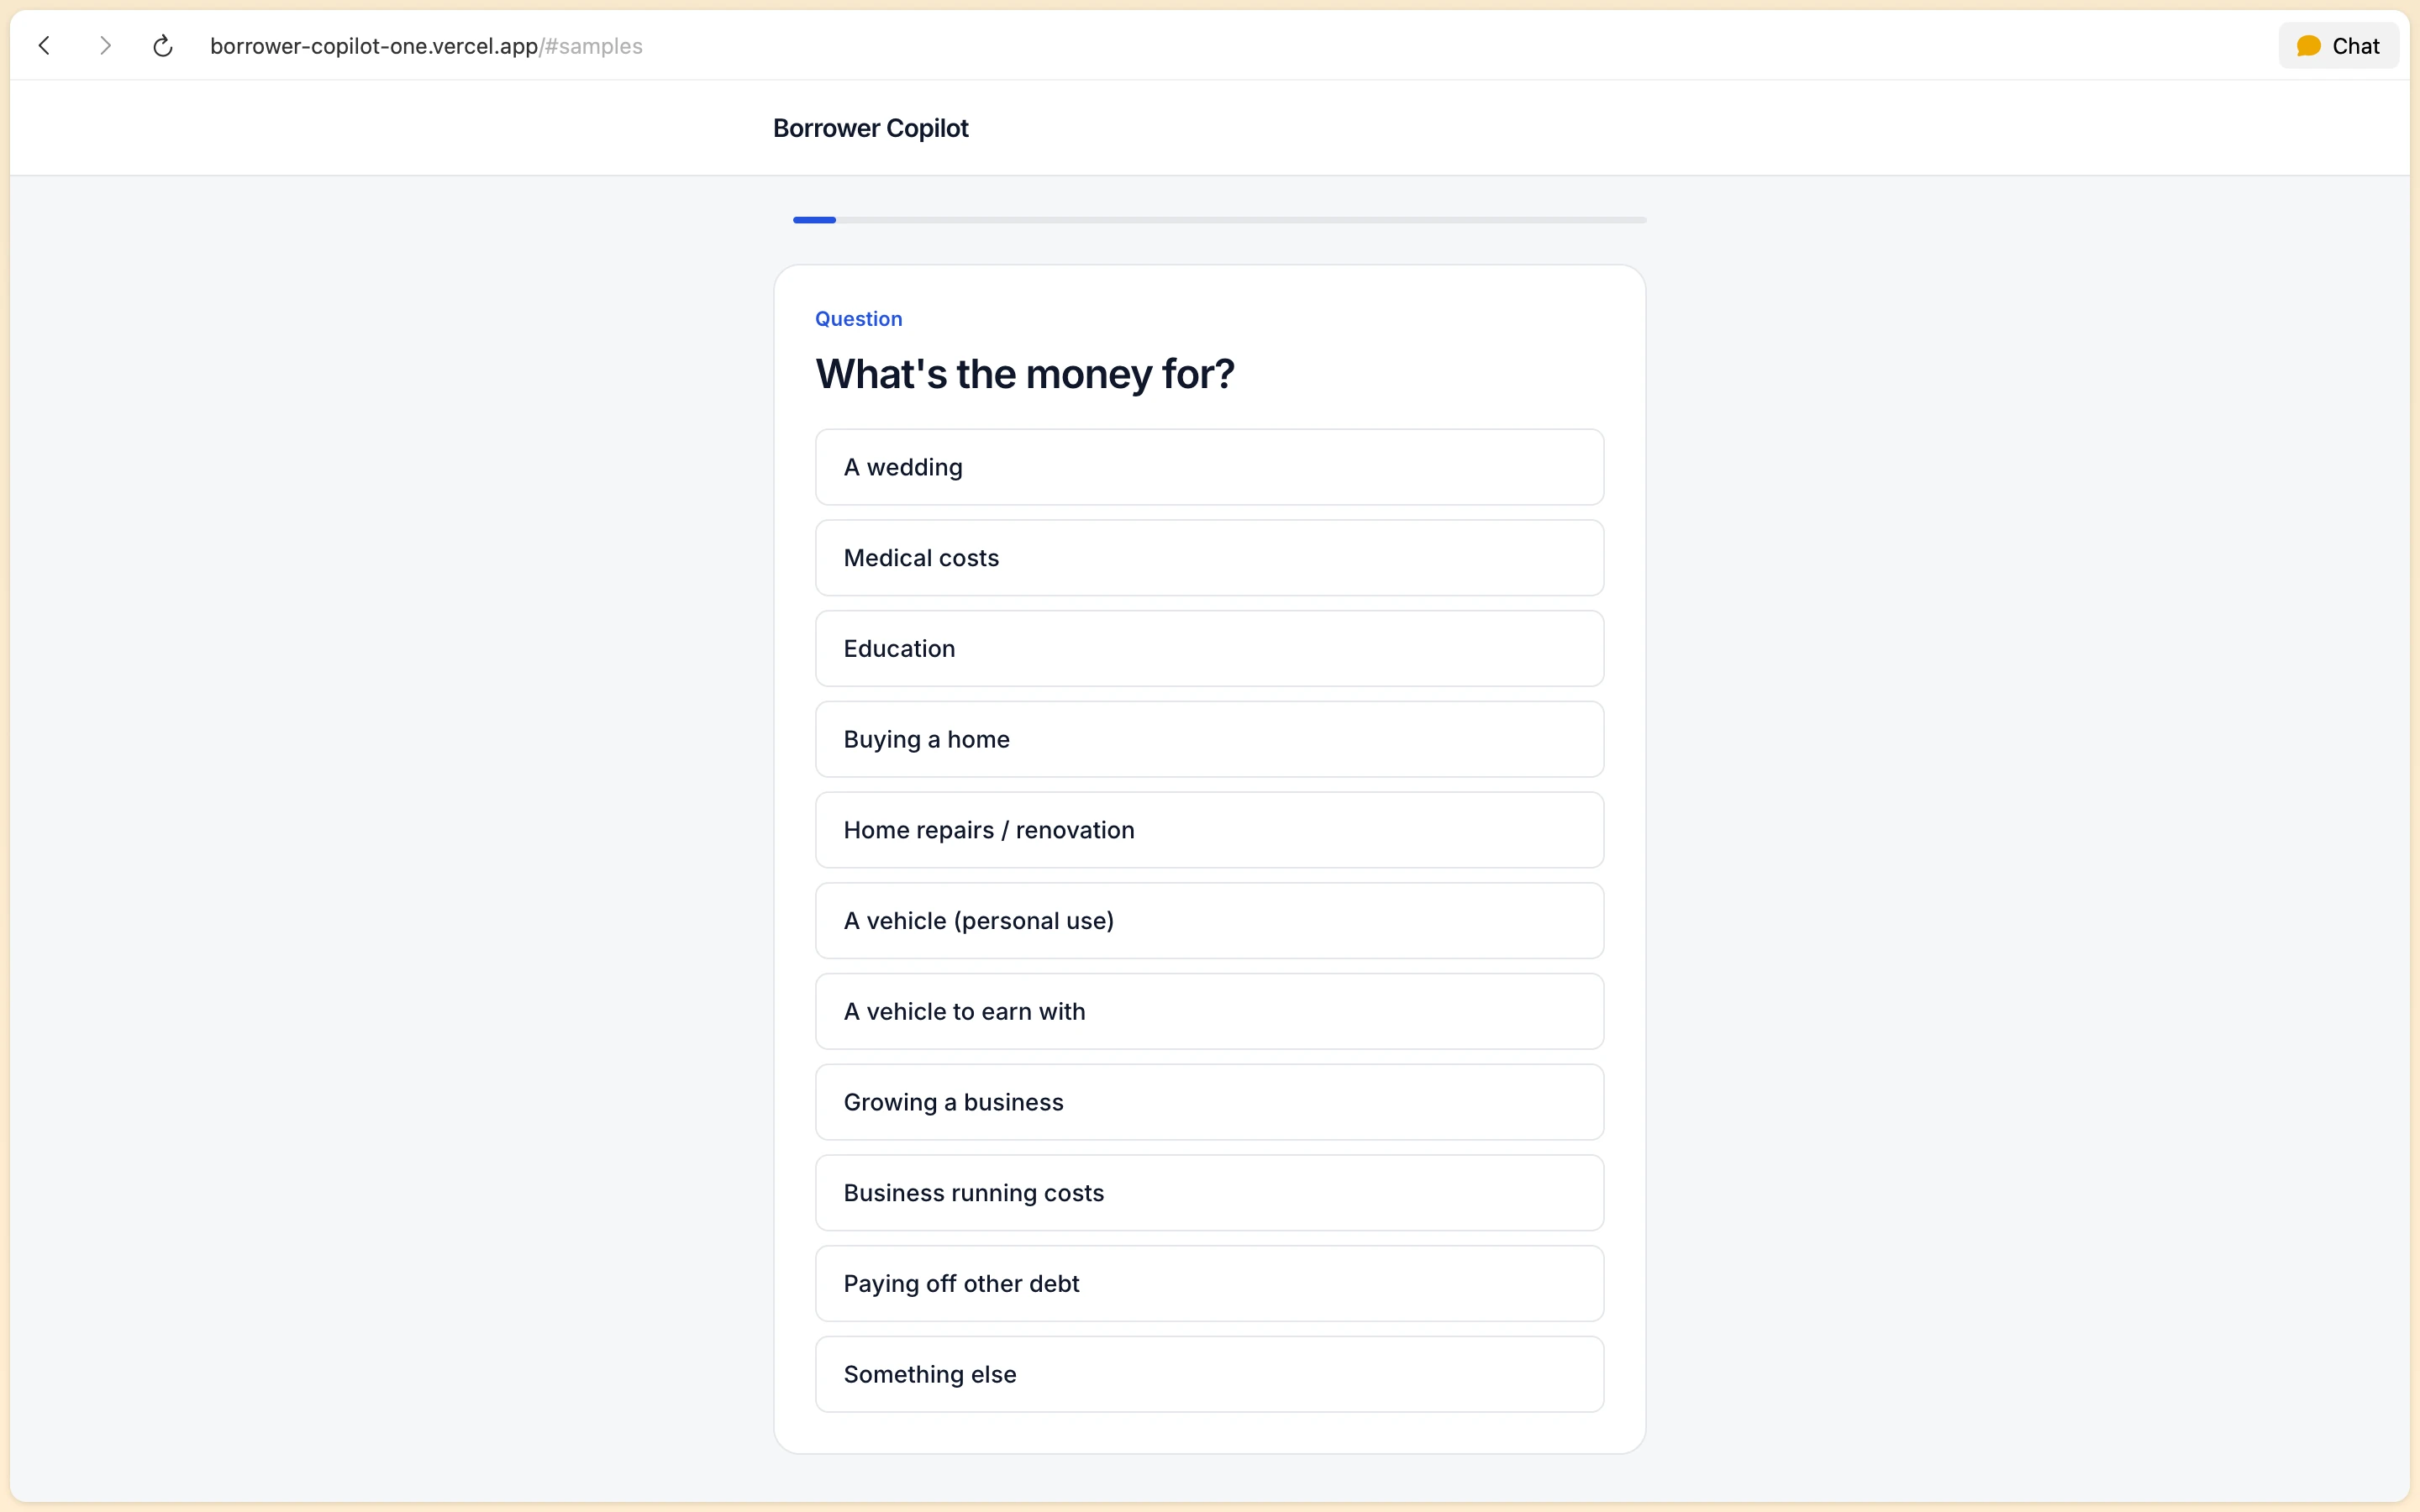
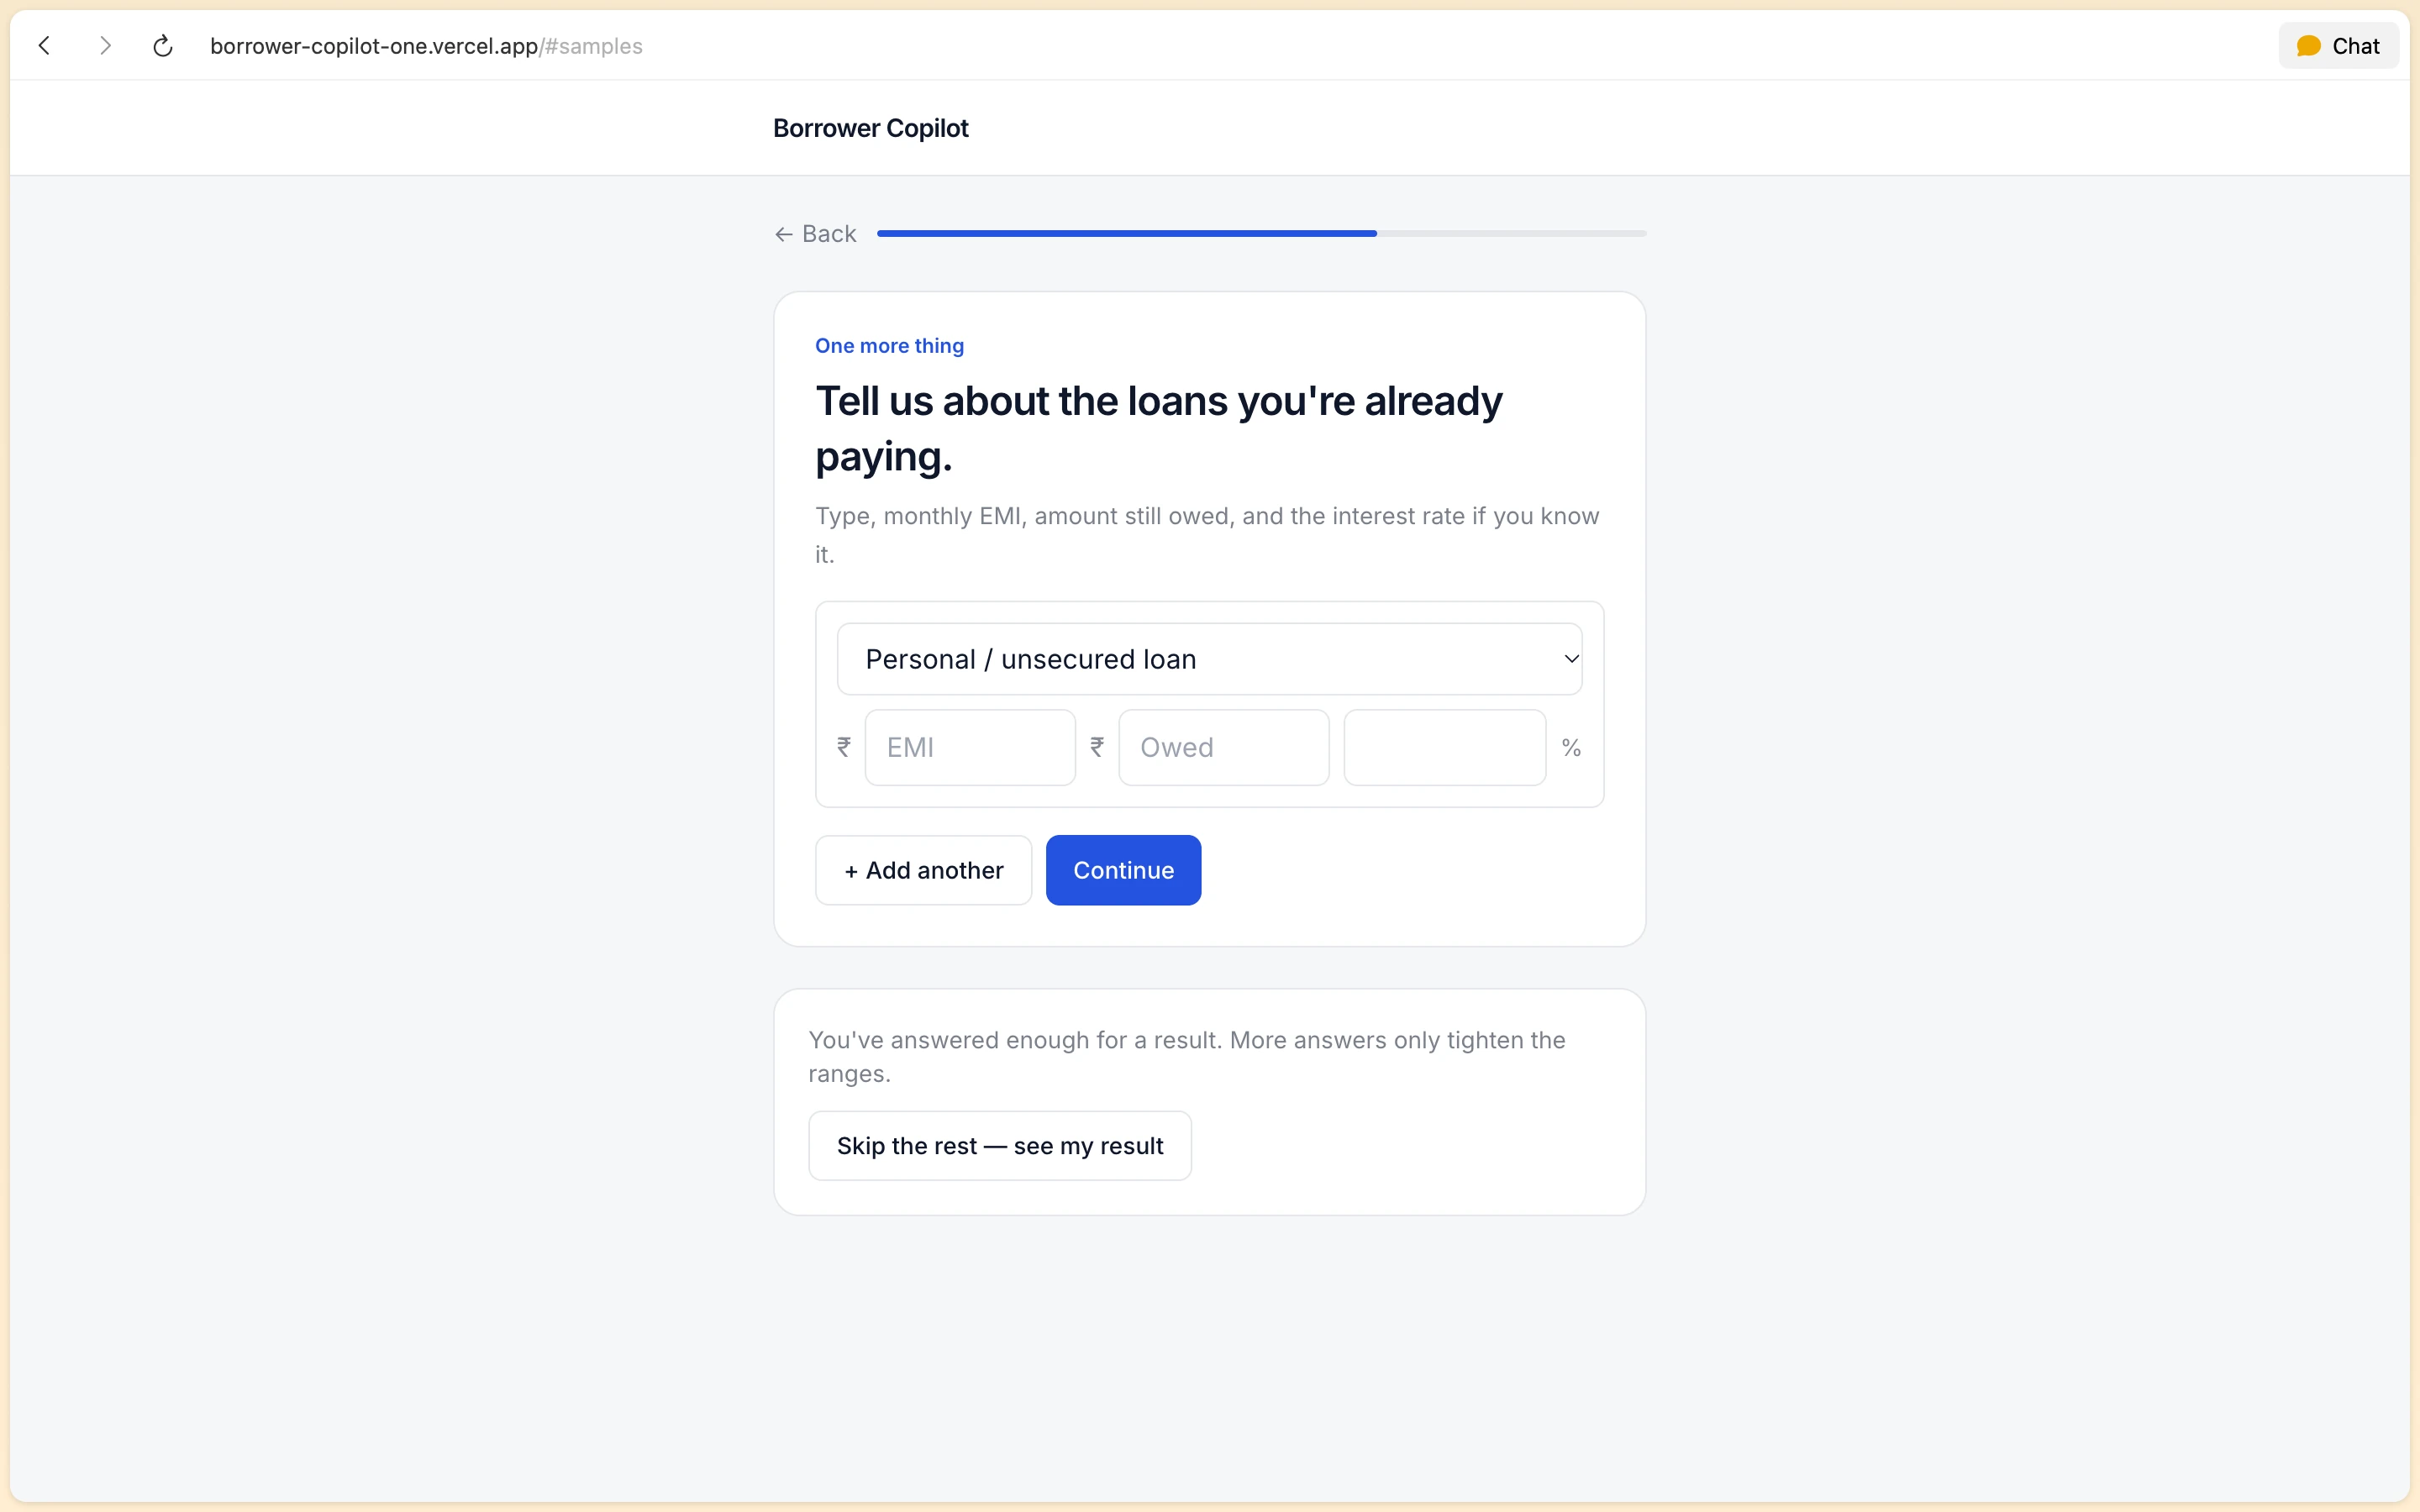
Answer the questions
One question at a time. Unsure answers are allowed, and you can skip to a result once there's enough.
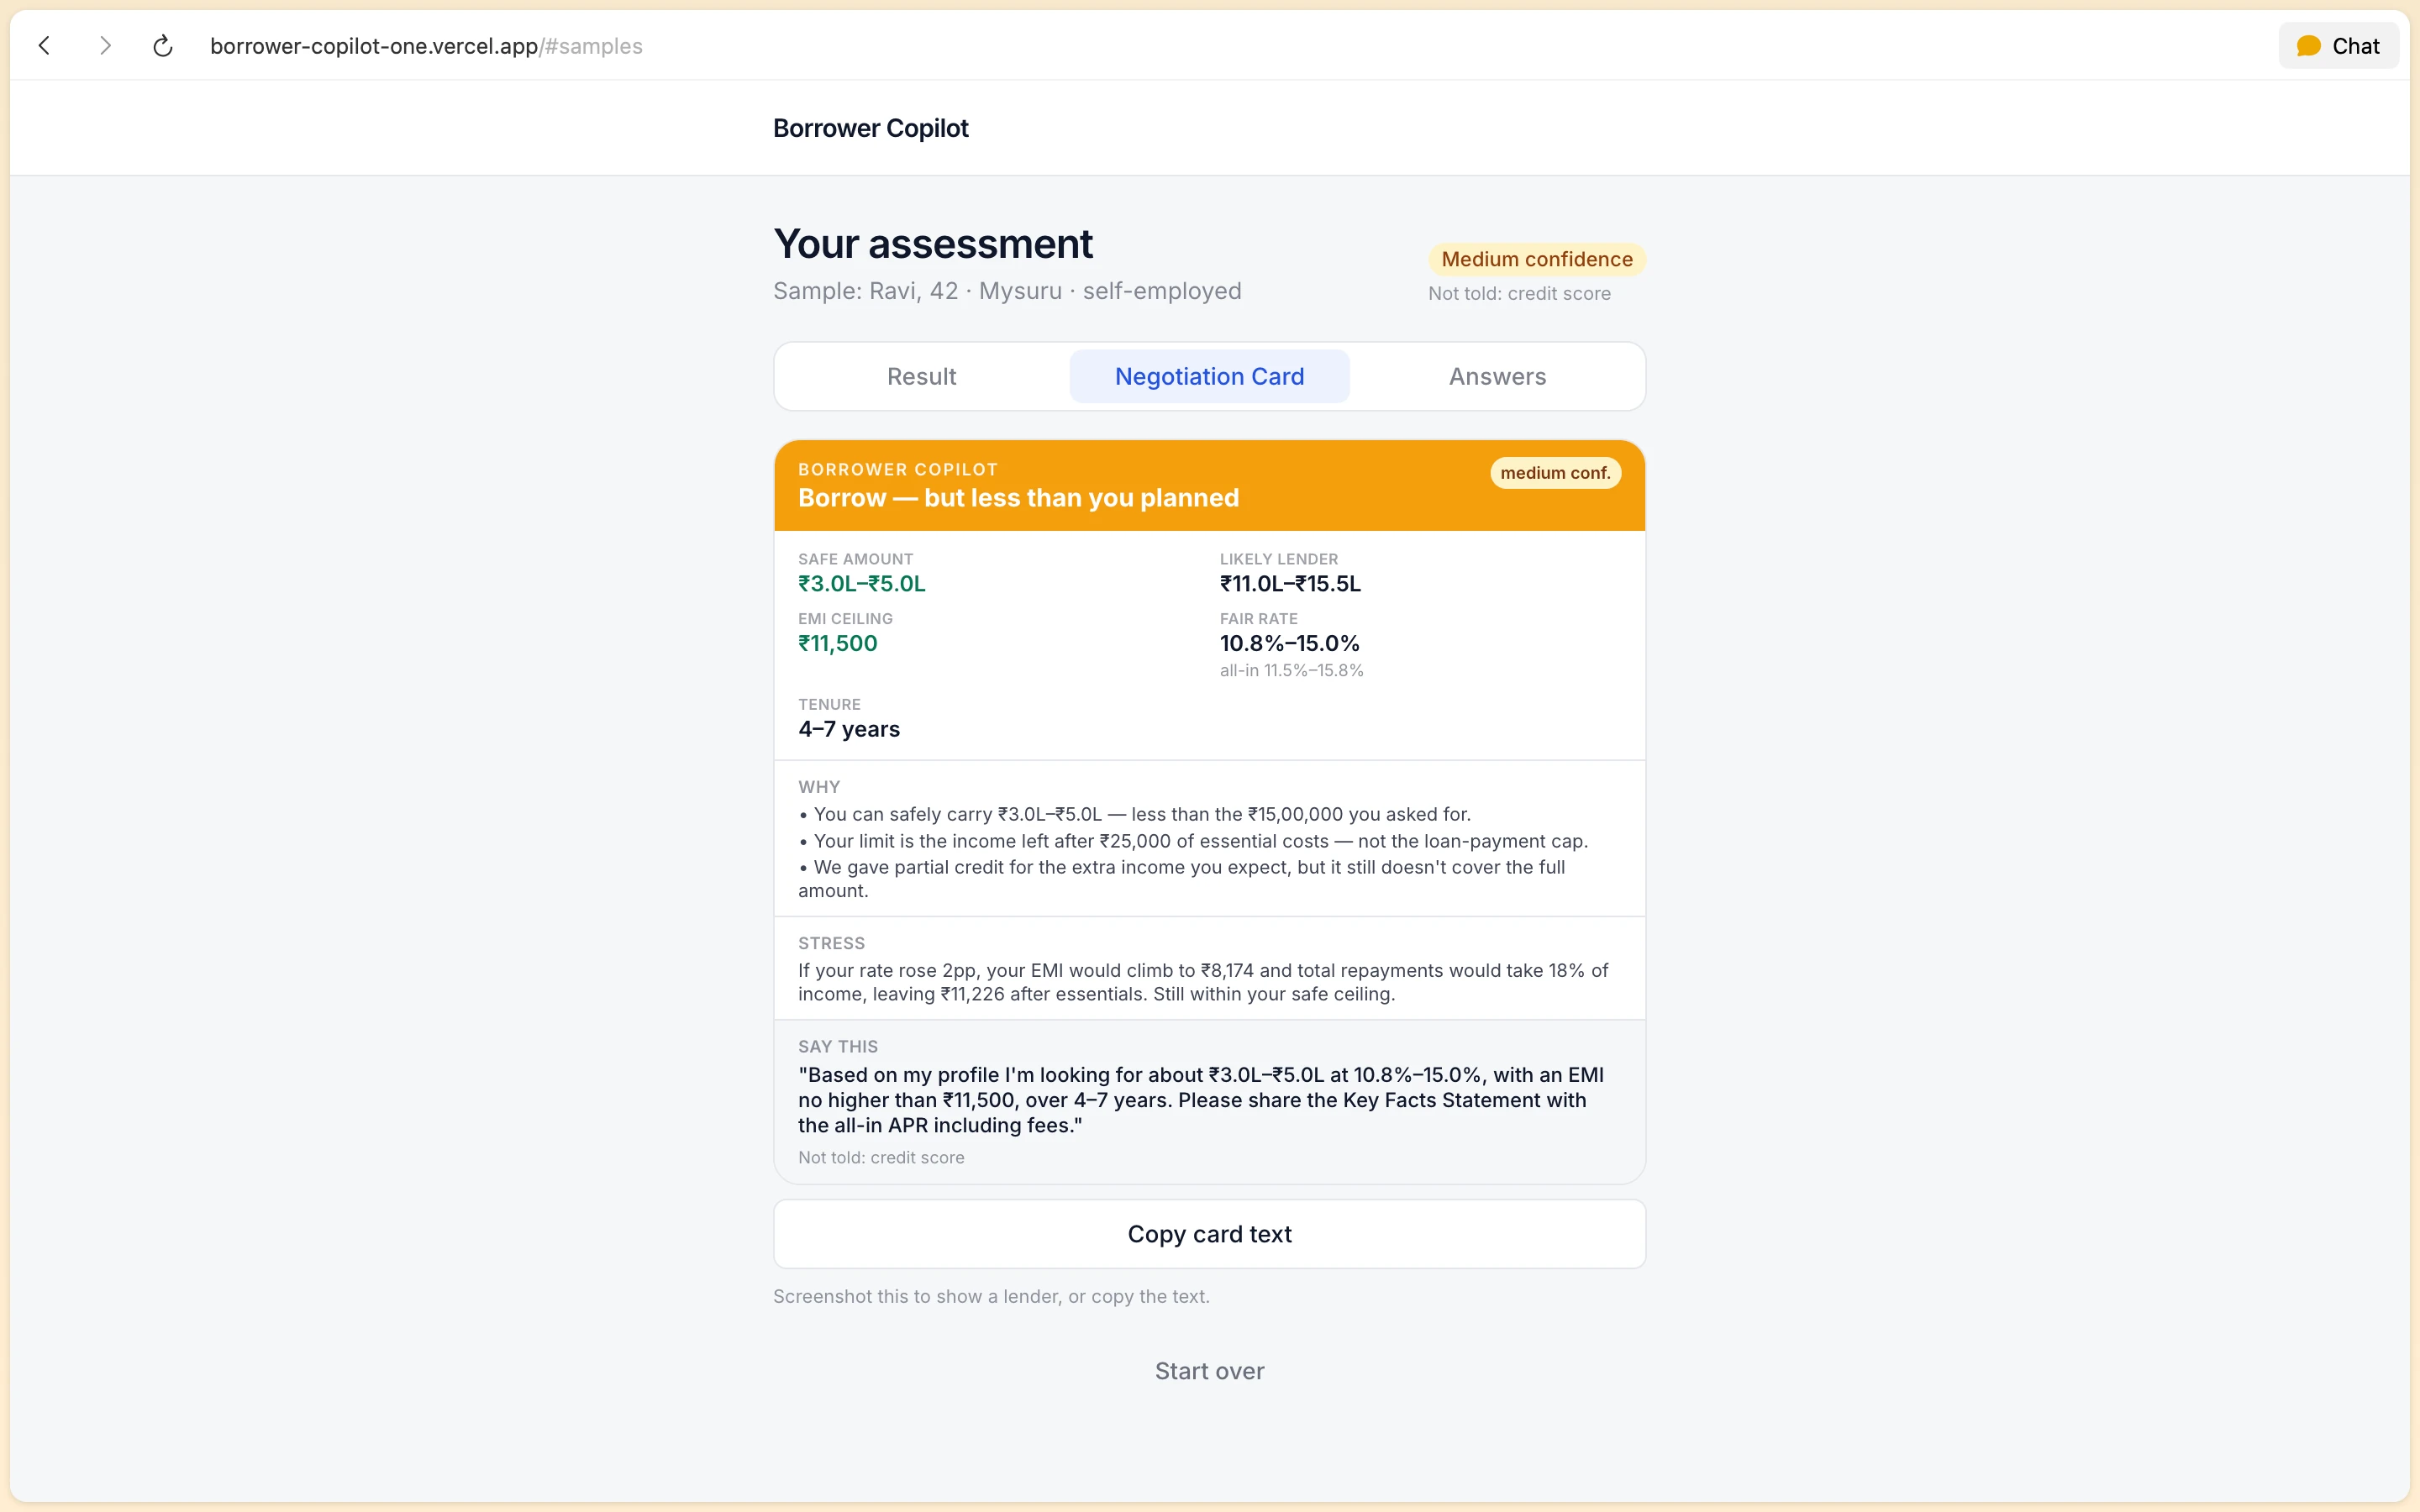
Get the result
The sample borrower Ravi: four outputs, each with the numbers behind it, and a Negotiation Card.
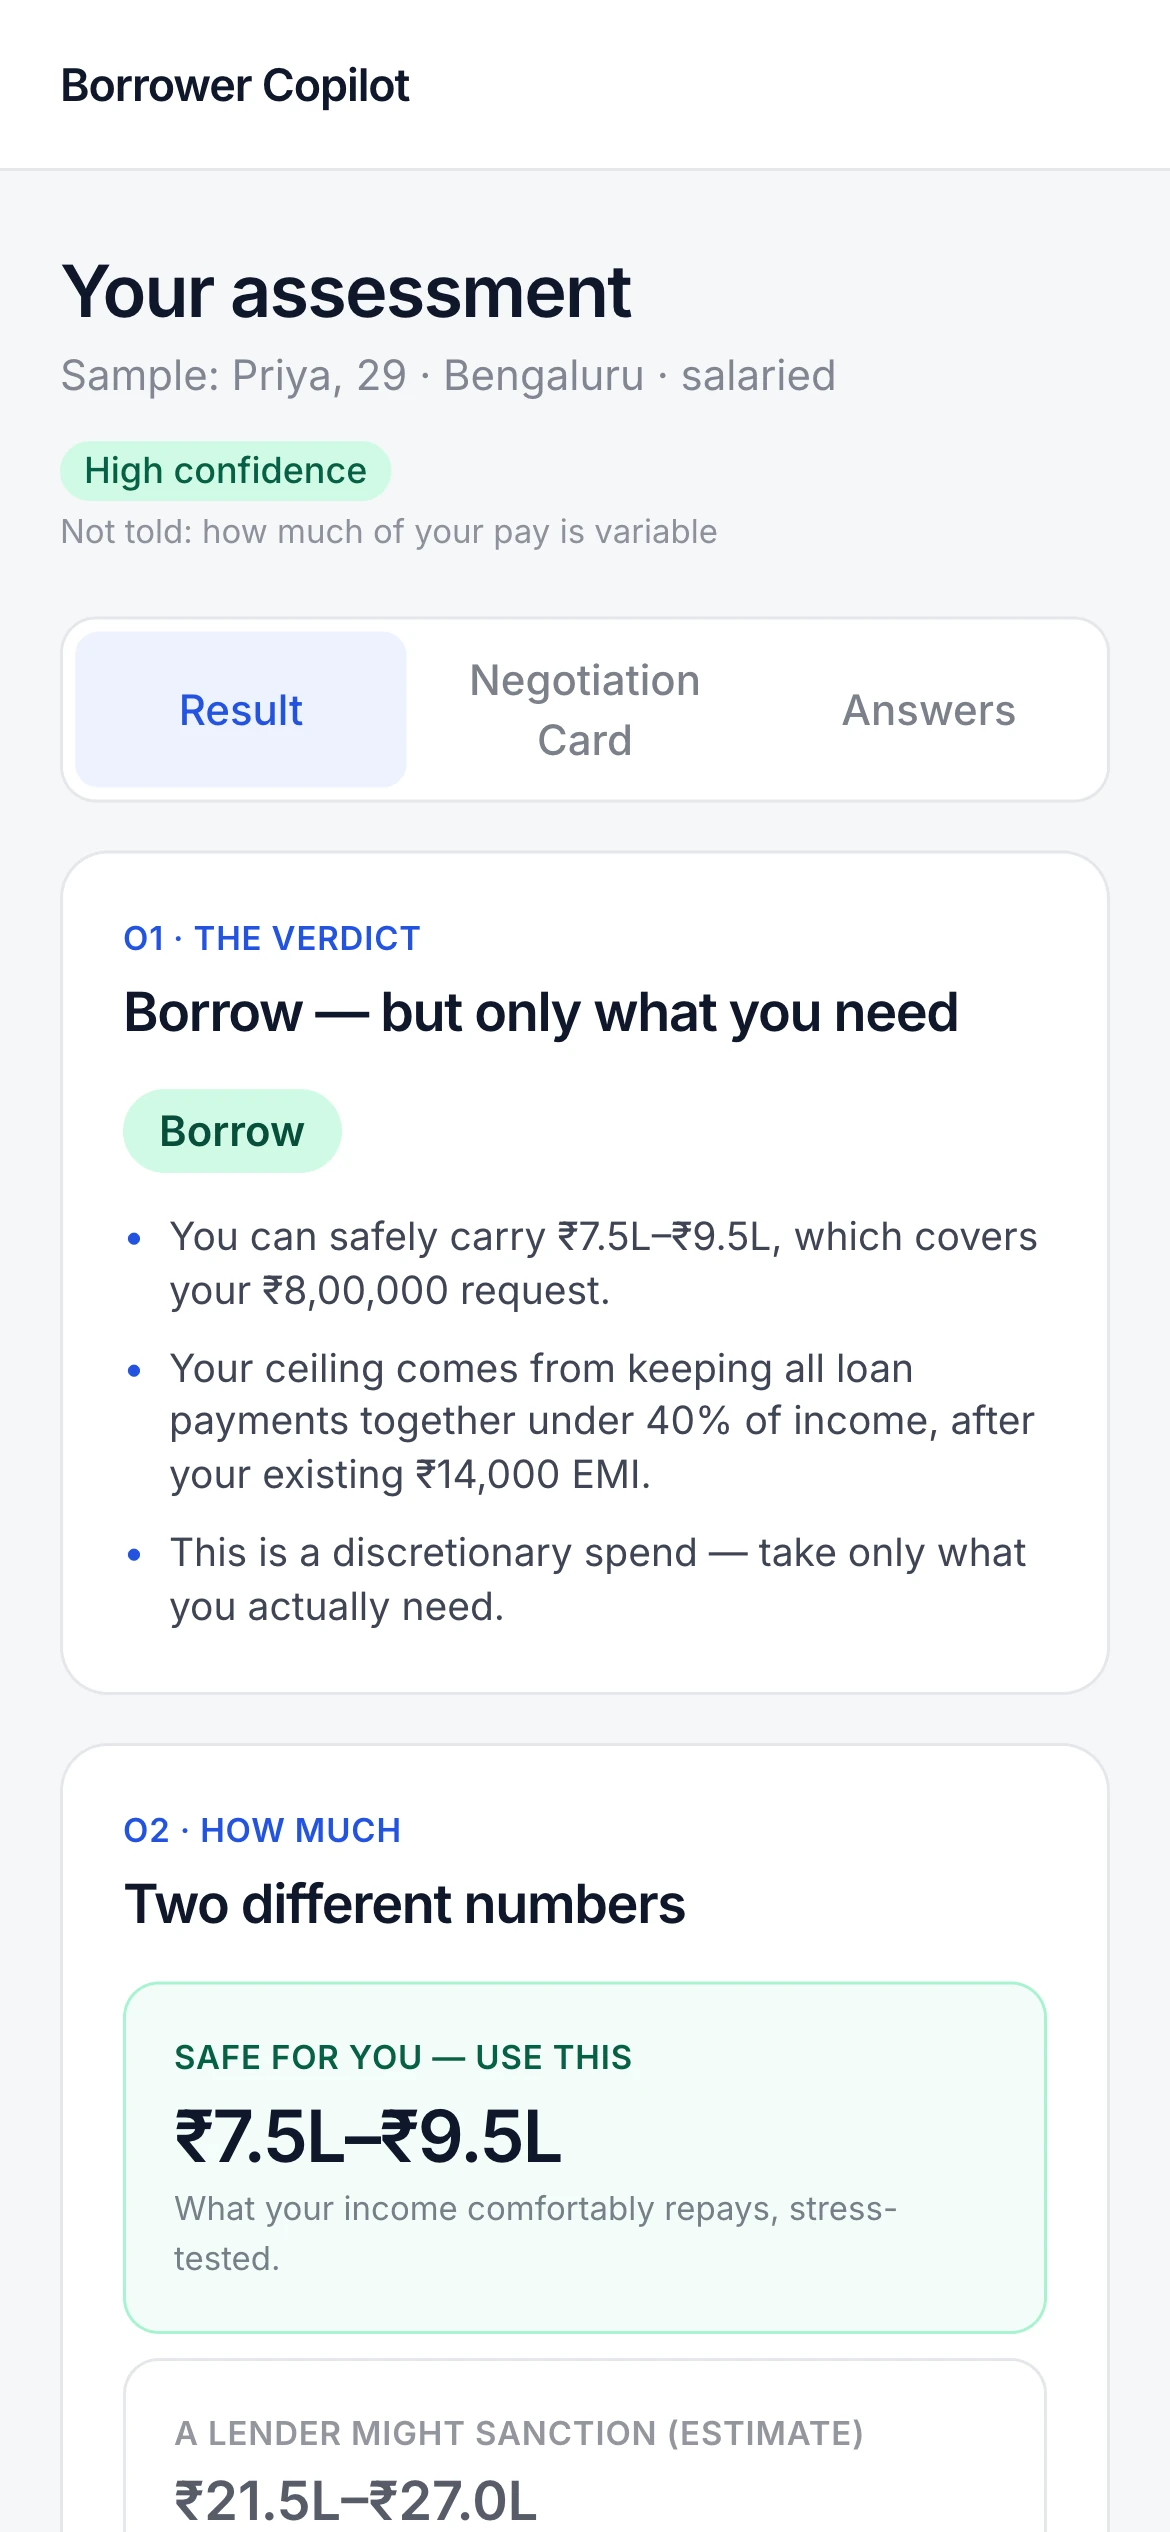
On mobile
Built mobile-first: the same flow on a phone, shown here with the sample borrower Priya.
The stack
- Frontend
- Next.js 14 (static export) · React 18 · TypeScript · Tailwind CSS
- Rules engine
- Pure TypeScript functions · Config-driven thresholds · IRR-based APR
- Testing
- Vitest · Testing Library
- Delivery
- Vercel
The result
78
automated tests across the rules, the question engine and the UI, all passing; every threshold and rate is documented in RULES.md
Source: npm test on the repo's main branch, run 4 Oct 2026
Related Service
Service 04
Product Build
Need a system like Borrower Copilot? I audit your workflows, build custom integrations, and hand over the keys in your accounts.
Related Reading
Automation or agent? Pick the boring one
Most problems sold as AI agents are automations wearing a costume. Here's the test I use before quoting either.
Read articleNobody in this business builds the model
What an AI studio actually makes, what it rents, and why the distinction should be on the invoice.
Read article
Start a project
Tell me what needs to change
Share your product and the work you need. I'll help you find the right scope and next step.